
Advertisement
- Switzerland
- /
- Chemicals
- /
- SWX:GIVN
Givaudan SA (VTX:GIVN) Half-Year Results Just Came Out: Here's What Analysts Are Forecasting For This Year
Last week, you might have seen that Givaudan SA (VTX:GIVN) released its interim result to the market. The early response was not positive, with shares down 3.0% to CHF3,647 in the past week. Results were roughly in line with estimates, with revenues of CHF3.9b and statutory earnings per share of CHF118. The analysts typically update their forecasts at each earnings report, and we can judge from their estimates whether their view of the company has changed or if there are any new concerns to be aware of. So we collected the latest post-earnings statutory consensus estimates to see what could be in store for next year.
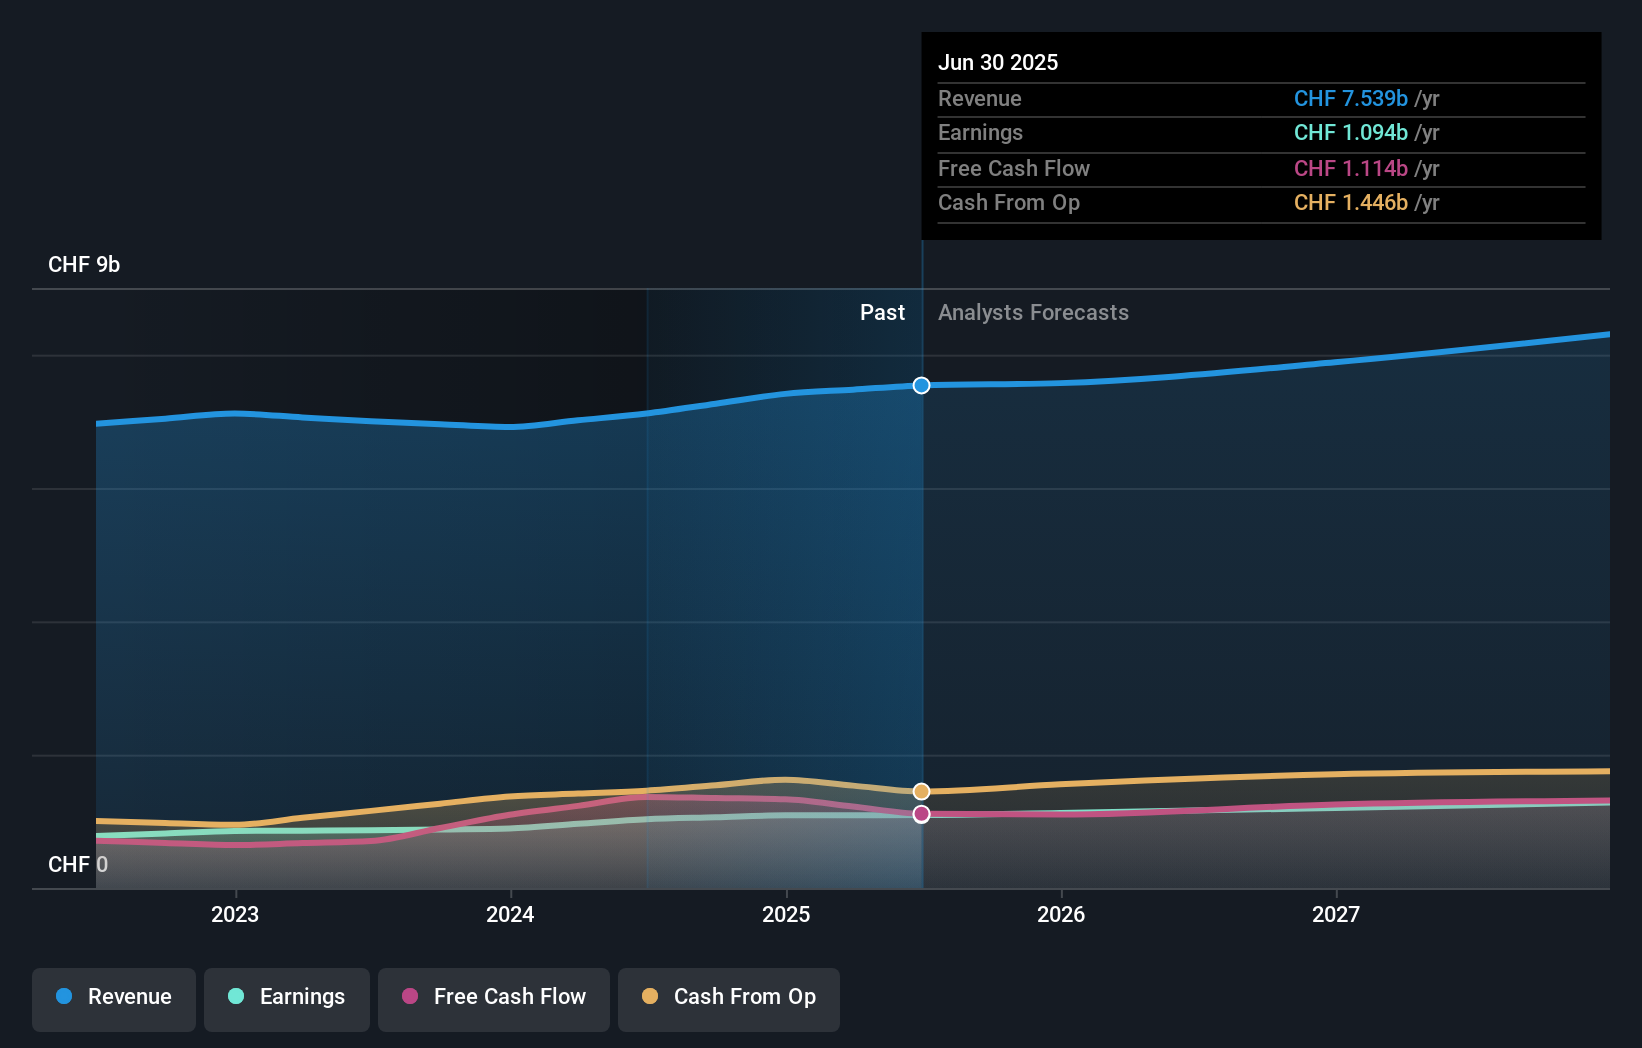
Taking into account the latest results, Givaudan's 19 analysts currently expect revenues in 2025 to be CHF7.57b, approximately in line with the last 12 months. Statutory per share are forecast to be CHF120, approximately in line with the last 12 months. Yet prior to the latest earnings, the analysts had been anticipated revenues of CHF7.64b and earnings per share (EPS) of CHF121 in 2025. The consensus analysts don't seem to have seen anything in these results that would have changed their view on the business, given there's been no major change to their estimates.
See our latest analysis for Givaudan
The analysts reconfirmed their price target of CHF4,150, showing that the business is executing well and in line with expectations. That's not the only conclusion we can draw from this data however, as some investors also like to consider the spread in estimates when evaluating analyst price targets. Currently, the most bullish analyst values Givaudan at CHF5,040 per share, while the most bearish prices it at CHF3,200. These price targets show that analysts do have some differing views on the business, but the estimates do not vary enough to suggest to us that some are betting on wild success or utter failure.
Of course, another way to look at these forecasts is to place them into context against the industry itself. It's pretty clear that there is an expectation that Givaudan's revenue growth will slow down substantially, with revenues to the end of 2025 expected to display 0.9% growth on an annualised basis. This is compared to a historical growth rate of 3.4% over the past five years. Compare this against other companies (with analyst forecasts) in the industry, which are in aggregate expected to see revenue growth of 4.1% annually. So it's pretty clear that, while revenue growth is expected to slow down, the wider industry is also expected to grow faster than Givaudan.
The Bottom Line
The most obvious conclusion is that there's been no major change in the business' prospects in recent times, with the analysts holding their earnings forecasts steady, in line with previous estimates. On the plus side, there were no major changes to revenue estimates; although forecasts imply they will perform worse than the wider industry. The consensus price target held steady at CHF4,150, with the latest estimates not enough to have an impact on their price targets.
Following on from that line of thought, we think that the long-term prospects of the business are much more relevant than next year's earnings. At Simply Wall St, we have a full range of analyst estimates for Givaudan going out to 2027, and you can see them free on our platform here..
Don't forget that there may still be risks. For instance, we've identified 1 warning sign for Givaudan that you should be aware of.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
MI

The Foxhole
Is Nvidia actually expensive at 32 times earnings? I think that number can melt faster than people realise.
77
MA
marcus_l38oa
Why would I fret over Nvidia results now? I think it's moment has gone. I will invert and see what companies can be the next Nvidia.
SE
sean_3pk06
Multiple has already melted 50 percent in the last year. It can melt another 50 percent from here in the next year?
 Mitchell Lawler
Market Insights
Which payment stocks actually get paid?
Every new payment app was supposed to kill Visa and Mastercard. Instead, they got bigger. So what does that mean for the payment stocks on your radar?
42
About SWX:GIVN
Givaudan
Engages in the manufacture, supply, and sale of fragrance, beauty, taste, and wellbeing products to the consumer goods industry.
Excellent balance sheet established dividend payer.
Similar Companies
Market Insights


Advertisement
Weekly Picks
RI


Rick_Orford on Starfighters Space ·
The 1960s Fighter Jet That Could Crack Open a $20 Billion Satellite Market
Fair Value:US$522.8% undervalued
69 followersusers have followed this narrative
4 commentsusers have commented on this narrative
11 likesusers have liked this narrative
TR


tripledub on Meta Platforms ·
The $135 Billion Bet That Should Make Every Shareholder Nervous
Fair Value:US$5862.7% undervalued
51 followersusers have followed this narrative
3 commentsusers have commented on this narrative
34 likesusers have liked this narrative
TA


Talos on Voyager Technologies ·
The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era
Fair Value:US$385.291.0% undervalued
45 followersusers have followed this narrative
0 commentsusers have commented on this narrative
5 likesusers have liked this narrative
IV

Ivoed on Uber Technologies ·
Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Fair Value:US$11630.7% undervalued
11 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
TI


tinyvalueinvestor on Magma Group Berhad ·
Magma Group Berhad: Wolo Mont Kiara KL Could Reshape the Group’s Growth Story
Fair Value:RM 0.4536.7% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
FA
FA_Trader on Magma Group Berhad ·
Magma Group Berhad: Stable Q2 Revenue Provides a Base for the Next Phase
Fair Value:RM 0.35.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
HU

Hunter_Z on Reservoir Link Energy Bhd ·
Reservoir Link Clears RM51.4m Impairment as Management Turns Cautiously Optimistic on FY2027
Fair Value:RM 0.650.8% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28023.9% undervalued
358 followersusers have followed this narrative
9 commentsusers have commented on this narrative
16 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9117.1% overvalued
207 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
KI

KiwiInvest on Amazon.com ·
Amazon's high growth, high tech segments propel its profits, while traditional segments plod along
Fair Value:US$475.0945.1% undervalued
231 followersusers have followed this narrative
1 commentusers have commented on this narrative
8 likesusers have liked this narrative


