
Advertisement
ALK-Abelló A/S's (CPH:ALK B): ALK-Abelló A/S, a pharmaceutical company, develops and markets products and services for allergy and allergic asthma in Europe, North America, and internationally. The ø21b market-cap company announced a latest loss of -ø50.0m on 31 December 2019 for its most recent financial year result. The most pressing concern for investors is ALK B’s path to profitability – when will it breakeven? Below I will provide a high-level summary of the industry analysts’ expectations for ALK B.
See our latest analysis for ALK-Abelló
According to the 4 industry analysts covering ALK B, the consensus is breakeven is near. They expect the company to post a final loss in 2020, before turning a profit of ø206m in 2021. ALK B is therefore projected to breakeven around a few months from now. How fast will ALK B have to grow each year in order to reach the breakeven point by 2021? Working backwards from analyst estimates, it turns out that they expect the company to grow 52% year-on-year, on average, which signals high confidence from analysts. If this rate turns out to be too aggressive, ALK B may become profitable much later than analysts predict.
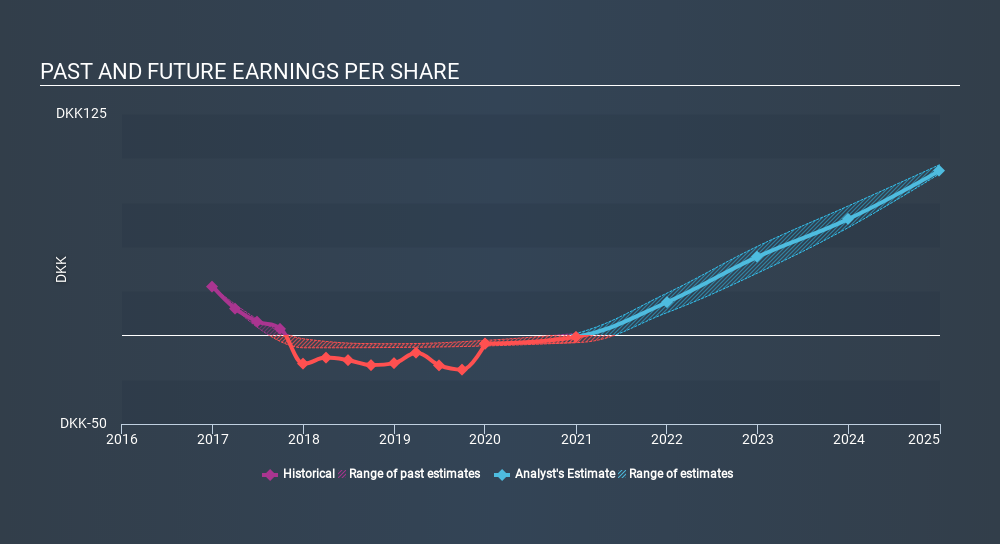
Given this is a high-level overview, I won’t go into details of ALK B’s upcoming projects, however, take into account that typically pharmaceuticals, depending on the stage of product development, have irregular periods of cash flow. So, a high growth rate is not out of the ordinary, particularly when a company is in a period of investment.
Before I wrap up, there’s one aspect worth mentioning. ALK B has managed its capital judiciously, with debt making up 23% of equity. This means that ALK B has predominantly funded its operations from equity capital,and its low debt obligation reduces the risk around investing in the loss-making company.
Next Steps:
There are too many aspects of ALK B to cover in one brief article, but the key fundamentals for the company can all be found in one place – ALK B’s company page on Simply Wall St. I’ve also compiled a list of key factors you should look at:
- Valuation: What is ALK B worth today? Has the future growth potential already been factored into the price? The intrinsic value infographic in our free research report helps visualize whether ALK B is currently mispriced by the market.
- Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on ALK-Abelló’s board and the CEO’s back ground.
- Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
If you spot an error that warrants correction, please contact the editor at editorial-team@simplywallst.com. This article by Simply Wall St is general in nature. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. Simply Wall St has no position in the stocks mentioned.
We aim to bring you long-term focused research analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Thank you for reading.
M

The Foxhole
Nasdaq will soon let you trade 23 hours a day. Buffett's advice was to barely trade at all.
77
s
sarah_c5otv
Discipline, Patience & Restraint will become a bigger and better edge now.

singhappily
Great news for anyone who felt their regrets were insufficiently spread across the day.
 Mitchell Lawler
Market Insights
What happens to energy stocks as the fix gets built?

Conflict around the Strait of Hormuz has led investors to oil and tankers. The trouble is, the antidote to the chokepoints is already being built, and it may not reward the same energy stocks.
73
About CPSE:ALK B
ALK-Abelló
An allergy solutions company, develops treatments for respiratory allergy, anaphylaxis, and food allergy and new disease areas in the European Union, the United Kingdom, Norway, Switzerland, the United States, Canada, Japan, China, and internationally.
Flawless balance sheet with proven track record.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CL


Clive_Thompson on Upside Gold ·
Upside Gold - New Technical Report Expected in Q1 2027 Could Re-Rate The Stock.
Fair Value:CA$1.552.7% undervalued
2 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
CO


composite32 on Archrock ·
AI Needs Power. Power Needs Gas. Gas Needs Compression: The Archrock Investment Thesis
Fair Value:US$44.8829.7% undervalued
35 followersusers have followed this narrative
2 commentsusers have commented on this narrative
3 likesusers have liked this narrative
JO


John_Eric on Advanced Energy Industries ·
AEIS Is Firing on Every Cylinder. My Problem Is the Safety Factor.
Fair Value:US$567.8653.8% undervalued
22 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
IS

isidrohg on Lam Research ·
The Memory Shortage Is Lam's Order Book — Whether It Persists Or Resolves
Fair Value:US$423.8532.0% undervalued
25 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
Recently Updated Narratives
RO


RockeTeller on Montage Gold ·
Montage Gold, Building West Africa’s Next 300Koz Producer, First Pour Late 2026, 5.88Moz Resource
Fair Value:CA$23.510.1% undervalued
18 followersusers have followed this narrative
5 commentsusers have commented on this narrative
1 likeusers have liked this narrative
OO

OOO97 on Vistra ·
VST is a conservative way to Ride America´s Hunger for AI Energy Demand (slightly undervalued at 140, estimated 171)
Fair Value:US$17117.7% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
GE


Genious_Trades on TOYO ·
The $14 Disconnect: Why the Market is not Correctly Pricing TOYO’s U.S. Solar Expansion
Fair Value:US$1570.6% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8326.6% undervalued
1488 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8918.3% undervalued
1648 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32722.4% undervalued
1664 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative


