
Last Update 19 Aug 26
Fair value Increased 6.00%532539: Future Returns Will Reflect New Seating Capacity And Modest Risk Balance
Analysts have lifted their price target for Uno Minda from about ₹1,254 to roughly ₹1,329, reflecting updated assumptions for slightly higher revenue growth, profit margins, and a marginally lower future P/E multiple.
What's in the News for Uno Minda
- The board has approved a greenfield manufacturing facility in Chhatrapati Sambhajinagar, Maharashtra, to support Uno Minda's entry into four wheeler passenger vehicle seating systems under the Uno Minda Tachi S Seating Private Limited joint venture with TACHI S Company Limited, Japan. The planned capital expenditure is about ₹3,200 million, and the joint venture has already secured an anchor customer order from an OEM. (Source: company key developments)
- A board meeting is scheduled on July 7, 2026, to consider and approve the new seating systems manufacturing project with a stated total cost of ₹320.00 crore. (Source: company key developments)
- A board meeting is scheduled on August 4, 2026, to consider the unaudited standalone financial results for the quarter ended June 30, 2026. (Source: company key developments)
- The annual general meeting on July 31, 2026, approved a final dividend of ₹1.75 per equity share at 87.5% and noted an interim dividend of ₹0.90 per equity share at 45% that was already paid for the financial year ended March 31, 2026. (Source: company key developments)
- A regulatory order was received on June 17, 2026, from the Office of the Commissioner of Customs, Nhava Sheva, for anti dumping duty on imported machinery, including tax or duty of ₹4,881,256, interest under Section 28AA of the Customs Act, 1962, and a penalty of ₹4,881,256. Uno Minda intends to contest the order and has stated it does not foresee any material impact on its financial, operational, or other activities. (Source: company key developments)
Valuation Changes for Uno Minda
- Fair value has risen slightly from about ₹1,253.89 to roughly ₹1,329.11.
- The discount rate is broadly unchanged, moving marginally from 14.43% to about 14.44%.
- The revenue growth assumption has edged up from around 17.50% to approximately 17.90%.
- The net profit margin estimate has moved modestly higher from about 6.79% to roughly 6.87%.
- The future P/E has eased slightly from about 50.60x to roughly 49.88x.
Key Takeaways
- Focus on EV and smart vehicle technologies, along with localization and strategic acquisitions, boosts innovation, margins, and reduces reliance on external partners.
- Capacity expansion, premiumization, and compliance with evolving safety standards support long-term revenue growth and operating leverage above industry averages.
- Aggressive expansion, overseas challenges, start-up costs, partnership risks, and weak export demand may constrain margins and limit earnings growth despite strong domestic momentum.
Catalysts
About Uno Minda- Manufactures and supplies auto components and systems in India and internationally.
- Substantial ongoing and planned investments in EV-specific components, ADAS, sensors, and smart electronics position Uno Minda for significant growth as regulations and consumer preferences shift towards electric, safer, and smarter vehicles; this is expected to expand revenue and improve margins as product mix becomes more value-accretive.
- The company's localizing of advanced components such as camera modules for ADAS and RPAS-formerly imported-enables cost competitiveness, improves margins, and supports higher content per vehicle as OEMs transition to more feature-rich, regulatory-compliant models.
- Robust order book and capacity expansions-tied to confirmed POs-across alloy wheels, lighting, and emerging EV product lines, coupled with multiple new plants coming online in FY26/27, are likely to support 1.5x or higher top-line growth relative to industry averages, driving future revenue and operating leverage.
- Growing demand driven by premiumisation (higher content per vehicle) and stricter safety norms (e.g. more airbags, LED lighting, ADAS) underpin a structural uplift in average realized revenue per unit and should support higher EBITDA margins as penetration of these technologies rises across segments.
- Strategic acquisition of JV partners' technology and stakes (e.g., Friwo) enables Uno Minda to gain proprietary control over key EV technologies, reducing dependency on external partners and strengthening both innovation capability and margin profile over the long term, as more revenue accrues from differentiated, own-IP products rather than lower-margin, commoditized components.
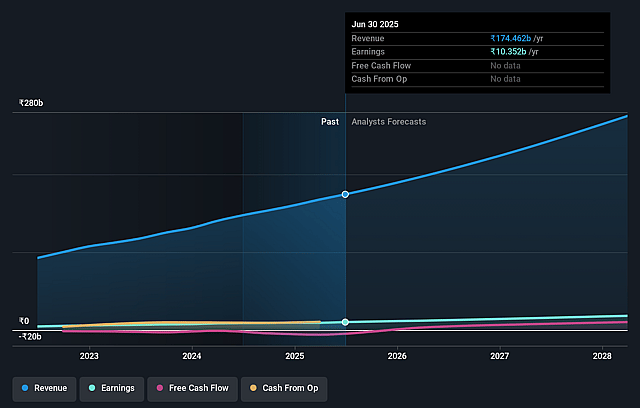
Uno Minda Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming Uno Minda's revenue will grow by 17.9% annually over the next 3 years.
- Analysts assume that profit margins will increase from 5.8% today to 6.9% in 3 years time.
- Analysts expect earnings to reach ₹23.3 billion (and earnings per share of ₹40.29) by about August 2029, up from ₹12.0 billion today. However, there is some disagreement amongst the analysts with the more bearish ones expecting earnings as low as ₹18.8 billion.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 49.9x on those 2029 earnings, down from 61.2x today. This future PE is greater than the current PE for the IN Auto Components industry at 27.9x.
- Analysts expect the number of shares outstanding to grow by 0.36% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 14.44%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Sustained high levels of growth CapEx and large numbers of simultaneous expansion projects may strain cash flows and increase net debt; with several new plants and high investment in emerging technologies, delays in achieving target asset turns or slower ramp-up in new businesses could pressure both net margins and earnings in the medium term.
- Continued underperformance and margin pressure in overseas businesses-especially in the European acoustics segment (Clarton Horn), which has faced declining volumes and difficulty achieving profitability at current scale-may weigh on consolidated margins and limit earnings growth if turnaround plans do not succeed.
- The company's margin trajectory is currently diluted by the ramp-up of a large number of new ventures and product lines, where start-up costs are expensed ahead of revenue generation; this structural drag may persist if new lines (e.g., EV powertrain castings, camera modules) take longer than expected to scale, limiting operating leverage and net profit growth over the next few years.
- Heavy investment and strategic reliance on partnerships and joint ventures for access to advanced technology (e.g., Friwo, Buehler, Inovance) could expose Uno Minda to risks if technology licensing agreements prove costly or if partner instability (as seen with Friwo's exit and Buehler's capital constraints) disrupts operations, ultimately compressing long-term margins and technological differentiation.
- Despite strong domestic momentum, declining or stagnating demand in export geographies (such as persistent European weakness and evolving OEM preferences) could hamper revenue diversification; if Indian auto sector growth slows or foreign EV makers mostly use global supply chains, Uno Minda may face headwinds in growing international earnings and market share.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of ₹1329.11 for Uno Minda based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of ₹1532.0, and the most bearish reporting a price target of just ₹970.0.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be ₹339.7 billion, earnings will come to ₹23.3 billion, and it would be trading on a PE ratio of 49.9x, assuming you use a discount rate of 14.4%.
- Given the current share price of ₹1275.0, the analyst price target of ₹1329.11 is 4.1% higher. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Uno Minda?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Legacy Components Will Struggle As EV Demand Surges
View narrative
Expansions And Localization Will Capture Secular EV And Auto Trends
View narrative