
Advertisement
Howard Marks put it nicely when he said that, rather than worrying about share price volatility, 'The possibility of permanent loss is the risk I worry about... and every practical investor I know worries about.' So it seems the smart money knows that debt - which is usually involved in bankruptcies - is a very important factor, when you assess how risky a company is. Importantly, Pointpack S.A. (WSE:PNT) does carry debt. But is this debt a concern to shareholders?
Why Does Debt Bring Risk?
Debt is a tool to help businesses grow, but if a business is incapable of paying off its lenders, then it exists at their mercy. In the worst case scenario, a company can go bankrupt if it cannot pay its creditors. While that is not too common, we often do see indebted companies permanently diluting shareholders because lenders force them to raise capital at a distressed price. Of course, the upside of debt is that it often represents cheap capital, especially when it replaces dilution in a company with the ability to reinvest at high rates of return. When we think about a company's use of debt, we first look at cash and debt together.
What Is Pointpack's Debt?
You can click the graphic below for the historical numbers, but it shows that as of December 2024 Pointpack had zł11.4m of debt, an increase on zł7.88m, over one year. However, it does have zł2.70m in cash offsetting this, leading to net debt of about zł8.71m.
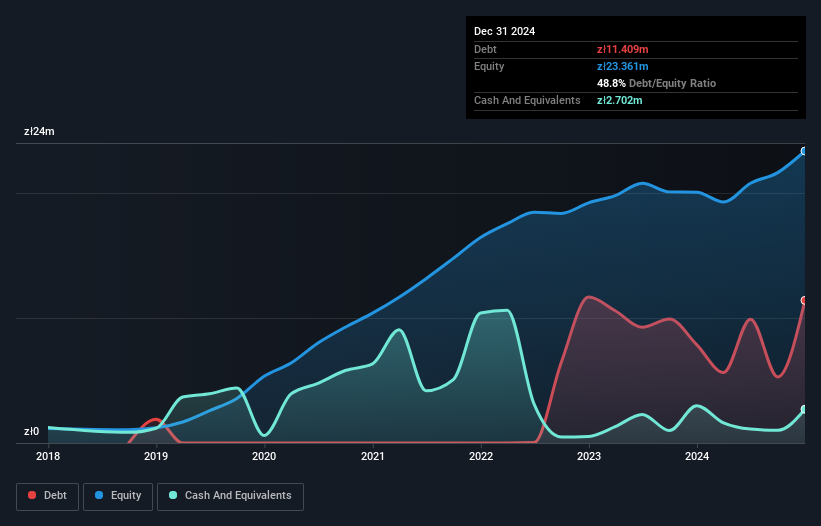
A Look At Pointpack's Liabilities
Zooming in on the latest balance sheet data, we can see that Pointpack had liabilities of zł31.8m due within 12 months and liabilities of zł2.54m due beyond that. Offsetting these obligations, it had cash of zł2.70m as well as receivables valued at zł14.9m due within 12 months. So it has liabilities totalling zł16.8m more than its cash and near-term receivables, combined.
This deficit is considerable relative to its market capitalization of zł26.9m, so it does suggest shareholders should keep an eye on Pointpack's use of debt. Should its lenders demand that it shore up the balance sheet, shareholders would likely face severe dilution.
Check out our latest analysis for Pointpack
We use two main ratios to inform us about debt levels relative to earnings. The first is net debt divided by earnings before interest, tax, depreciation, and amortization (EBITDA), while the second is how many times its earnings before interest and tax (EBIT) covers its interest expense (or its interest cover, for short). Thus we consider debt relative to earnings both with and without depreciation and amortization expenses.
Pointpack has net debt of just 1.0 times EBITDA, indicating that it is certainly not a reckless borrower. And this view is supported by the solid interest coverage, with EBIT coming in at 8.6 times the interest expense over the last year. Even more impressive was the fact that Pointpack grew its EBIT by 318% over twelve months. That boost will make it even easier to pay down debt going forward. The balance sheet is clearly the area to focus on when you are analysing debt. But you can't view debt in total isolation; since Pointpack will need earnings to service that debt. So when considering debt, it's definitely worth looking at the earnings trend. Click here for an interactive snapshot.
Finally, a company can only pay off debt with cold hard cash, not accounting profits. So it's worth checking how much of that EBIT is backed by free cash flow. Over the last three years, Pointpack saw substantial negative free cash flow, in total. While that may be a result of expenditure for growth, it does make the debt far more risky.
Our View
Pointpack's conversion of EBIT to free cash flow and level of total liabilities definitely weigh on it, in our esteem. But the good news is it seems to be able to grow its EBIT with ease. Looking at all the angles mentioned above, it does seem to us that Pointpack is a somewhat risky investment as a result of its debt. That's not necessarily a bad thing, since leverage can boost returns on equity, but it is something to be aware of. The balance sheet is clearly the area to focus on when you are analysing debt. However, not all investment risk resides within the balance sheet - far from it. For example, we've discovered 4 warning signs for Pointpack that you should be aware of before investing here.
If you're interested in investing in businesses that can grow profits without the burden of debt, then check out this free list of growing businesses that have net cash on the balance sheet.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
MI

The Foxhole
Berkshire sold Visa and Mastercard. Ackman just bought both. So whose "smart money" are you actually following?
106
 Andrew Legget
Market Insights
Great earnings season, but are the earnings real?

At first glance, this was the strongest earnings season in years. But when you look at where the growth actually came from, the story splits into two very different pictures.
85
About WSE:PNT
Pointpack
Engages in the provision of service solutions for the trade and courier industry in Poland.
Excellent balance sheet with low risk.
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.576.1% undervalued
45 followersusers have followed this narrative
0 commentsusers have commented on this narrative
12 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17012.9% undervalued
11 followersusers have followed this narrative
2 commentsusers have commented on this narrative
2 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8752.9% undervalued
5 followersusers have followed this narrative
0 commentsusers have commented on this narrative
4 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0929.5% undervalued
4 followersusers have followed this narrative
1 commentusers have commented on this narrative
2 likesusers have liked this narrative
Recently Updated Narratives
LU


LunaRodas on Medtronic ·
MDT | Medtronic: What They Said vs. What They Did
Fair Value:US$115.3821.4% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
MO

Mohammed_Ahmed_Aleen on Saudi Telecom ·
Could LEAP 2026 Make stc Worth SAR 46.50 Per Share?
Fair Value:ر.س46.494.6% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
TI

TimLee on SBS Nexus Berhad ·
SBS Nexus Delivers Strong Q2 Profit Rebound as Digital Branding Drives Growth
Fair Value:RM 0.3560.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28021.2% undervalued
372 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$7.31k73.5% undervalued
128 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9120.8% overvalued
217 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative


