
Advertisement
- Malaysia
- /
- Retail Distributors
- /
- KLSE:MARCO
Our Take On The Returns On Capital At Marco Holdings Berhad (KLSE:MARCO)
What are the early trends we should look for to identify a stock that could multiply in value over the long term? Amongst other things, we'll want to see two things; firstly, a growing return on capital employed (ROCE) and secondly, an expansion in the company's amount of capital employed. Basically this means that a company has profitable initiatives that it can continue to reinvest in, which is a trait of a compounding machine. Although, when we looked at Marco Holdings Berhad (KLSE:MARCO), it didn't seem to tick all of these boxes.
What is Return On Capital Employed (ROCE)?
For those who don't know, ROCE is a measure of a company's yearly pre-tax profit (its return), relative to the capital employed in the business. Analysts use this formula to calculate it for Marco Holdings Berhad:
Return on Capital Employed = Earnings Before Interest and Tax (EBIT) ÷ (Total Assets - Current Liabilities)
0.13 = RM27m ÷ (RM222m - RM10m) (Based on the trailing twelve months to June 2020).
So, Marco Holdings Berhad has an ROCE of 13%. In absolute terms, that's a satisfactory return, but compared to the Retail Distributors industry average of 6.2% it's much better.
Check out our latest analysis for Marco Holdings Berhad
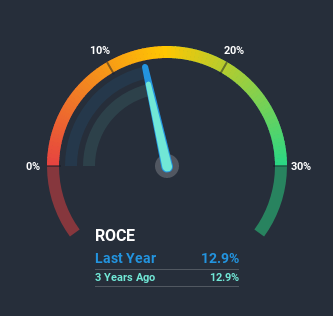
While the past is not representative of the future, it can be helpful to know how a company has performed historically, which is why we have this chart above. If you're interested in investigating Marco Holdings Berhad's past further, check out this free graph of past earnings, revenue and cash flow.
What Does the ROCE Trend For Marco Holdings Berhad Tell Us?
When we looked at the ROCE trend at Marco Holdings Berhad, we didn't gain much confidence. Over the last five years, returns on capital have decreased to 13% from 18% five years ago. Meanwhile, the business is utilizing more capital but this hasn't moved the needle much in terms of sales in the past 12 months, so this could reflect longer term investments. It may take some time before the company starts to see any change in earnings from these investments.
What We Can Learn From Marco Holdings Berhad's ROCE
To conclude, we've found that Marco Holdings Berhad is reinvesting in the business, but returns have been falling. Unsurprisingly then, the total return to shareholders over the last five years has been flat. All in all, the inherent trends aren't typical of multi-baggers, so if that's what you're after, we think you might have more luck elsewhere.
Since virtually every company faces some risks, it's worth knowing what they are, and we've spotted 3 warning signs for Marco Holdings Berhad (of which 1 is potentially serious!) that you should know about.
If you want to search for solid companies with great earnings, check out this free list of companies with good balance sheets and impressive returns on equity.
If you’re looking to trade Marco Holdings Berhad, open an account with the lowest-cost* platform trusted by professionals, Interactive Brokers. Their clients from over 200 countries and territories trade stocks, options, futures, forex, bonds and funds worldwide from a single integrated account. Promoted
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
This article by Simply Wall St is general in nature. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
*Interactive Brokers Rated Lowest Cost Broker by StockBrokers.com Annual Online Review 2020
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com.
MI

The Foxhole
Berkshire sold Visa and Mastercard. Ackman just bought both. So whose "smart money" are you actually following?
136
MA
marcus_l38oa
American Express is the bigger bet of Buffet than Mastercard and Visa. They are still holding it.
ZO
zoe_vi5fn
lol. what we should be discussing is Berkshire's cash pile. Close to 400 billion now.
 Andrew Legget
Market Insights
Great earnings season, but are the earnings real?
At first glance, this was the strongest earnings season in years. But when you look at where the growth actually came from, the story splits into two very different pictures.
85
About KLSE:MARCO
Marco Holdings Berhad
An investment holding company, engages in wholesale and distribution of timepieces, consumer technology, electronic products, and electronic musical instruments in Malaysia.
Flawless balance sheet with proven track record.
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.576.0% undervalued
44 followersusers have followed this narrative
0 commentsusers have commented on this narrative
12 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17015.9% undervalued
11 followersusers have followed this narrative
2 commentsusers have commented on this narrative
2 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8752.7% undervalued
6 followersusers have followed this narrative
0 commentsusers have commented on this narrative
4 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0929.5% undervalued
4 followersusers have followed this narrative
1 commentusers have commented on this narrative
2 likesusers have liked this narrative
Recently Updated Narratives
WO


Womble on Nebius Group ·
Prepare for Nebius Group's Revenue to Soar by 49.8%
Fair Value:US$259.9723.2% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
WO
Womble on ServiceNow ·
ServiceNow's 16% Revenue Growth Will Excite Future Investors
Fair Value:US$19024.8% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
WO

Womble on Credo Technology Group Holding ·
Credo Technology Expects Robust 27% Revenue Growth in Five Years
Fair Value:US$215.013.9% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28022.3% undervalued
372 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$7.31k73.2% undervalued
128 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9119.3% overvalued
217 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative


