
Advertisement
Some say volatility, rather than debt, is the best way to think about risk as an investor, but Warren Buffett famously said that 'Volatility is far from synonymous with risk.' So it might be obvious that you need to consider debt, when you think about how risky any given stock is, because too much debt can sink a company. We note that Precot Limited (NSE:PRECOT) does have debt on its balance sheet. But is this debt a concern to shareholders?
Why Does Debt Bring Risk?
Debt and other liabilities become risky for a business when it cannot easily fulfill those obligations, either with free cash flow or by raising capital at an attractive price. Part and parcel of capitalism is the process of 'creative destruction' where failed businesses are mercilessly liquidated by their bankers. While that is not too common, we often do see indebted companies permanently diluting shareholders because lenders force them to raise capital at a distressed price. Having said that, the most common situation is where a company manages its debt reasonably well - and to its own advantage. When we examine debt levels, we first consider both cash and debt levels, together.
What Is Precot's Net Debt?
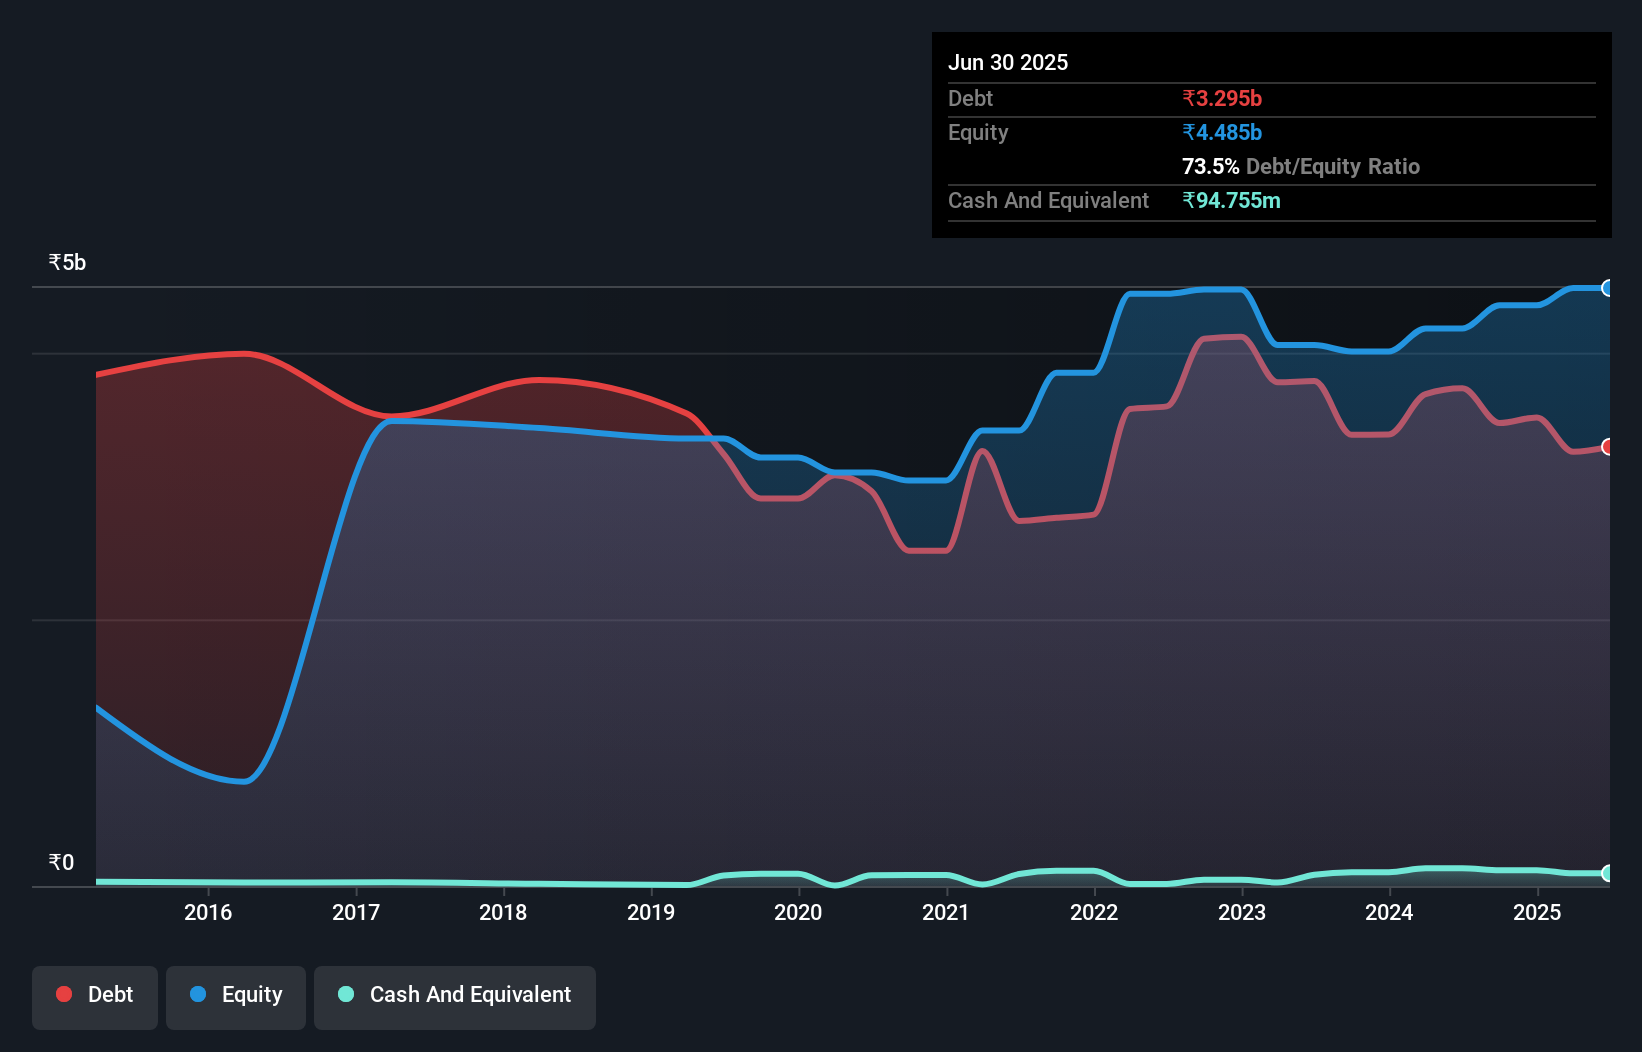
The image below, which you can click on for greater detail, shows that Precot had debt of ₹3.29b at the end of March 2025, a reduction from ₹3.73b over a year. However, it also had ₹94.8m in cash, and so its net debt is ₹3.20b.
How Healthy Is Precot's Balance Sheet?
According to the last reported balance sheet, Precot had liabilities of ₹3.70b due within 12 months, and liabilities of ₹1.20b due beyond 12 months. On the other hand, it had cash of ₹94.8m and ₹1.41b worth of receivables due within a year. So it has liabilities totalling ₹3.40b more than its cash and near-term receivables, combined.
This deficit is considerable relative to its market capitalization of ₹4.98b, so it does suggest shareholders should keep an eye on Precot's use of debt. Should its lenders demand that it shore up the balance sheet, shareholders would likely face severe dilution.
See our latest analysis for Precot
We measure a company's debt load relative to its earnings power by looking at its net debt divided by its earnings before interest, tax, depreciation, and amortization (EBITDA) and by calculating how easily its earnings before interest and tax (EBIT) cover its interest expense (interest cover). This way, we consider both the absolute quantum of the debt, as well as the interest rates paid on it.
Precot has a debt to EBITDA ratio of 2.8 and its EBIT covered its interest expense 3.8 times. This suggests that while the debt levels are significant, we'd stop short of calling them problematic. Looking on the bright side, Precot boosted its EBIT by a silky 54% in the last year. Like a mother's loving embrace of a newborn that sort of growth builds resilience, putting the company in a stronger position to manage its debt. The balance sheet is clearly the area to focus on when you are analysing debt. But you can't view debt in total isolation; since Precot will need earnings to service that debt. So when considering debt, it's definitely worth looking at the earnings trend. Click here for an interactive snapshot.
Finally, while the tax-man may adore accounting profits, lenders only accept cold hard cash. So it's worth checking how much of that EBIT is backed by free cash flow. During the last two years, Precot produced sturdy free cash flow equating to 67% of its EBIT, about what we'd expect. This free cash flow puts the company in a good position to pay down debt, when appropriate.
Our View
On our analysis Precot's EBIT growth rate should signal that it won't have too much trouble with its debt. But the other factors we noted above weren't so encouraging. For instance it seems like it has to struggle a bit to cover its interest expense with its EBIT. Considering this range of data points, we think Precot is in a good position to manage its debt levels. But a word of caution: we think debt levels are high enough to justify ongoing monitoring. The balance sheet is clearly the area to focus on when you are analysing debt. However, not all investment risk resides within the balance sheet - far from it. For instance, we've identified 3 warning signs for Precot that you should be aware of.
Of course, if you're the type of investor who prefers buying stocks without the burden of debt, then don't hesitate to discover our exclusive list of net cash growth stocks, today.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
MI

The Foxhole
The world's in stitches over robots sprinting into walls. I still think they're the answer to our productivity problem.
87
DE
devon_jd150
What you have missed is that this event happened last year too. Last year the number was 21 seconds. This year it beat Bolt. That's 60% improvement in an year. Now extrapolate this in many axes of work that Robots can come and fill in. The physical productivity and AI boom is just starting.
LE
LeverageIsLovely
I can't pick a company. But I can pick a person. With no doubt that's Musk. Optimus for blue collar productivity increase and xAI for white collar productivity increase. Did anyone dabble with GrokBot here?
 Andrew Legget
Market Insights
Great earnings season, but are the earnings real?

At first glance, this was the strongest earnings season in years. But when you look at where the growth actually came from, the story splits into two very different pictures.
75
About NSEI:PRECOT
Precot
Manufactures and sells yarn and technical textile products in India and internationally.
Excellent balance sheet with slight risk.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.576.1% undervalued
43 followersusers have followed this narrative
0 commentsusers have commented on this narrative
12 likesusers have liked this narrative
TR


tripledub on Meta Platforms ·
The $135 Billion Bet That Should Make Every Shareholder Nervous
Fair Value:US$5862.4% undervalued
63 followersusers have followed this narrative
3 commentsusers have commented on this narrative
34 likesusers have liked this narrative
TA


Talos on Voyager Technologies ·
The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era
Fair Value:US$385.291.3% undervalued
68 followersusers have followed this narrative
0 commentsusers have commented on this narrative
6 likesusers have liked this narrative
IV

Ivoed on Uber Technologies ·
Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Fair Value:US$11634.8% undervalued
14 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
LU


LunaRodas on Science Applications International ·
SAIC | Science Applications International: What They Said vs. What They Did
Fair Value:US$119.247.5% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
AN

Anthony_Lee on Lotus Technology ·
Tech and Tradition: Lotus Technology’s Compound Formula in Luxury EVs
Fair Value:US$2.5354.2% undervalued
2 followersusers have followed this narrative
5 commentsusers have commented on this narrative
1 likeusers have liked this narrative
EP

Epstein_Research on Dryden Gold ·
Dryden Gold continues to expand & de-risk its flagship Gold Rock project!
Fair Value:CA$173.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28021.3% undervalued
369 followersusers have followed this narrative
9 commentsusers have commented on this narrative
16 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9120.8% overvalued
214 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
JO


John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$7.31k73.5% undervalued
125 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative

