
Advertisement
David Iben put it well when he said, 'Volatility is not a risk we care about. What we care about is avoiding the permanent loss of capital.' So it seems the smart money knows that debt - which is usually involved in bankruptcies - is a very important factor, when you assess how risky a company is. As with many other companies Etherstack plc (ASX:ESK) makes use of debt. But should shareholders be worried about its use of debt?
Why Does Debt Bring Risk?
Debt and other liabilities become risky for a business when it cannot easily fulfill those obligations, either with free cash flow or by raising capital at an attractive price. If things get really bad, the lenders can take control of the business. However, a more common (but still painful) scenario is that it has to raise new equity capital at a low price, thus permanently diluting shareholders. Having said that, the most common situation is where a company manages its debt reasonably well - and to its own advantage. The first thing to do when considering how much debt a business uses is to look at its cash and debt together.
Check out our latest analysis for Etherstack
How Much Debt Does Etherstack Carry?
You can click the graphic below for the historical numbers, but it shows that Etherstack had US$2.43m of debt in June 2024, down from US$2.74m, one year before. However, it does have US$1.36m in cash offsetting this, leading to net debt of about US$1.08m.
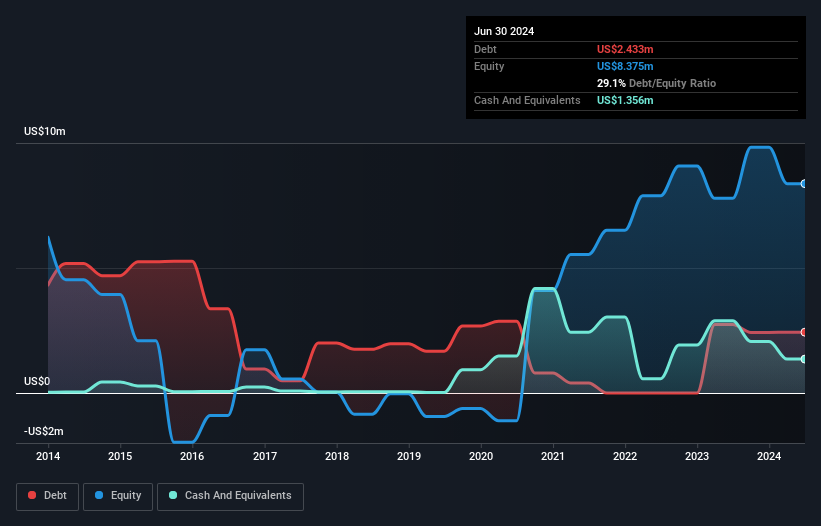
A Look At Etherstack's Liabilities
We can see from the most recent balance sheet that Etherstack had liabilities of US$3.40m falling due within a year, and liabilities of US$2.88m due beyond that. On the other hand, it had cash of US$1.36m and US$3.47m worth of receivables due within a year. So its liabilities outweigh the sum of its cash and (near-term) receivables by US$1.46m.
Given Etherstack has a market capitalization of US$19.5m, it's hard to believe these liabilities pose much threat. However, we do think it is worth keeping an eye on its balance sheet strength, as it may change over time.
We measure a company's debt load relative to its earnings power by looking at its net debt divided by its earnings before interest, tax, depreciation, and amortization (EBITDA) and by calculating how easily its earnings before interest and tax (EBIT) cover its interest expense (interest cover). Thus we consider debt relative to earnings both with and without depreciation and amortization expenses.
Even though Etherstack's debt is only 1.8, its interest cover is really very low at 1.7. This does suggest the company is paying fairly high interest rates. In any case, it's safe to say the company has meaningful debt. Notably, Etherstack made a loss at the EBIT level, last year, but improved that to positive EBIT of US$360k in the last twelve months. The balance sheet is clearly the area to focus on when you are analysing debt. But you can't view debt in total isolation; since Etherstack will need earnings to service that debt. So if you're keen to discover more about its earnings, it might be worth checking out this graph of its long term earnings trend.
But our final consideration is also important, because a company cannot pay debt with paper profits; it needs cold hard cash. So it is important to check how much of its earnings before interest and tax (EBIT) converts to actual free cash flow. Over the last year, Etherstack saw substantial negative free cash flow, in total. While investors are no doubt expecting a reversal of that situation in due course, it clearly does mean its use of debt is more risky.
Our View
Both Etherstack's conversion of EBIT to free cash flow and its interest cover were discouraging. At least its level of total liabilities gives us reason to be optimistic. Taking the abovementioned factors together we do think Etherstack's debt poses some risks to the business. So while that leverage does boost returns on equity, we wouldn't really want to see it increase from here. The balance sheet is clearly the area to focus on when you are analysing debt. However, not all investment risk resides within the balance sheet - far from it. To that end, you should be aware of the 2 warning signs we've spotted with Etherstack .
At the end of the day, it's often better to focus on companies that are free from net debt. You can access our special list of such companies (all with a track record of profit growth). It's free.
Valuation is complex, but we're here to simplify it.
Discover if Etherstack might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
M

The Foxhole
Nasdaq will soon let you trade 23 hours a day. Buffett's advice was to barely trade at all.
912
s
sarah_c5otv
Discipline, Patience & Restraint will become a bigger and better edge now.

singhappily
Great news for anyone who felt their regrets were insufficiently spread across the day.
 Mitchell Lawler
Market Insights
What happens to energy stocks as the fix gets built?

Conflict around the Strait of Hormuz has led investors to oil and tankers. The trouble is, the antidote to the chokepoints is already being built, and it may not reward the same energy stocks.
84
About ASX:ESK
Etherstack
A wireless technology company, engages in the development, manufacture, licensing, and sale of mission critical radio technologies to equipment manufacturers and network operators in the United Kingdom, the United States, Europe, Japan, and Australia.
Low risk with imperfect balance sheet.
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Buffalo Potash ·
Under the radar: This $78M stock controls a $1.5B project and it’ll start producing in a few months
Fair Value:CA$1.0625.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
CO


composite32 on Archrock ·
AI Needs Power. Power Needs Gas. Gas Needs Compression: The Archrock Investment Thesis
Fair Value:US$44.8831.5% undervalued
37 followersusers have followed this narrative
2 commentsusers have commented on this narrative
3 likesusers have liked this narrative
JO


John_Eric on Advanced Energy Industries ·
AEIS Is Firing on Every Cylinder. My Problem Is the Safety Factor.
Fair Value:US$567.8653.7% undervalued
22 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
IS

isidrohg on Lam Research ·
The Memory Shortage Is Lam's Order Book — Whether It Persists Or Resolves
Fair Value:US$423.8528.7% undervalued
26 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
Recently Updated Narratives
HO

hongjuan_p6tor on DSC Holdings ·
DSC is not a second car dealer like Carvana but a used car dealer enabler
Fair Value:US$3.32103.9% overvalued
1 followerusers have followed this narrative
1 commentusers have commented on this narrative
0 likesusers have liked this narrative
TI

TimLee on 3REN Berhad ·
3REN Berhad Is Powering the Semiconductor Ecosystem and Smart Manufacturing
Fair Value:RM 0.6843.4% undervalued
6 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
KA

KASHIF_RIAZ_ on MCB Bank ·
MCB Bank: high-quality income anchor — 9% yield, cheap earnings, modest upside
Fair Value:PK₨45011.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8324.9% undervalued
1494 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8917.0% undervalued
1652 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32721.0% undervalued
1669 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
Trending Discussion


PE
peng_i7fl6 on DSC Holdings ·
What stood out to me in this piece is how Zou draws a clear line between DSC and platforms like Carvana. DSC doesn't sell cars itself — it sits behind dealers and provides the operating system and transaction services. Once you frame it that way, the 90% market share starts to mean something real. Dealers run their daily work on the system: listings, pricing, inventory. The data accumulates bit by bit, and that's not something a competitor can buy its way into. You can't just throw money at it and get tens of thousands of dealers to switch systems.Her point about EVs was practical too. More brands, more models, more trim levels — dealer SKU management has gotten a lot messier, and pricing moves fast. Relying on gut feel from the old days doesn't cut it anymore. That demand isn't something the company invented; the industry just got to this point on its own.On the stock, her answer was honest. Management can't control short-term price action after listing, so they focus on running the business and delivering results. That reads more credible than pumping a narrative.The things I'd watch: whether dealer retention holds up, and whether the data and AI tools eventually show up as real revenue. A good story still has to pass the financials.
0
|0