
Last Update 18 Sep 26
Fair value Decreased 3.62%ALO: Large Contract Wins And Margin Gains Will Support Higher Future P/E
Alstom’s updated analyst price target edges lower to €21.10 from €21.89, reflecting a blend of recent target cuts and increases, as analysts reassess fair value, discount rate assumptions and medium term profitability expectations.
Analyst Commentary
Recent research on Alstom shows a mix of optimism and caution, with price targets ranging from €20 to €28 and different views on how the company might balance growth and execution risks over time.
Bullish Takeaways
- Bullish analysts highlight the higher €28 price target as a sign that they see room for upside if Alstom delivers on its medium term profitability goals.
- The decision by JPMorgan to lift its target from €27 to €28 suggests confidence that current execution plans can support a higher fair value than previously assumed.
- Supportive views appear to lean on Alstom’s ability to convert its project pipeline into stable earnings, which feeds into more constructive valuation models.
- Bullish analysts generally see recent volatility in targets as an opportunity for long term investors who are comfortable with execution risk.
Bearish Takeaways
- Bearish analysts point to the €20 target as a reminder that there are questions around execution and profitability that could limit upside in the near term.
- The cut from €22 to €20 reflects a more cautious stance on how quickly Alstom can deliver on its plans, which translates into more conservative valuation assumptions.
- Less optimistic views focus on potential pressure on margins and cash generation, which can weigh on how analysts value the stock.
- These more guarded targets signal that some analysts want clearer evidence of consistent operational delivery before assigning higher fair values to Alstom.
What’s in the News for Alstom
- Alstom signed contracts worth over €1.2b with TransPennine Express to supply 29 five car battery electric multiple units and provide an initial eight year maintenance service, creating more than 350 jobs in Derby and supporting around 5,500 roles in its UK supply chain. Source: TransPennine Express contract announcement.
- The company secured a $4.7b agreement with VIA Rail Canada to deliver 313 new Adessia passenger rail cars plus a 15 year technical support and spare parts deal, with work spread across several Canadian sites and hundreds of skilled jobs expected. Source: VIA Rail Canada contract announcement.
- Alstom reported a new locomotives contract in the Africa, Middle East and Central Asia region valued at about €800m, with client details to be shared at a later date. Source: company client announcement.
- The group received a statement of objections from the French Financial Markets Authority related to financial communications and share trading in an investigation that started in 2021/22, which Alstom intends to contest. Source: French AMF proceedings disclosure.
- Alstom entered a global exclusive memorandum of understanding with Graphene Manufacturing Group to test graphene based products for rail HVAC systems, with the aim of developing applications for this material in rail infrastructure. Source: company client announcement.
Valuation Changes for Alstom
- Fair Value has moved slightly lower to €21.10 from €21.89, which trims the implied upside embedded in recent models.
- Discount Rate has edged down to 8.66% from 8.90%, which marginally lifts the present value of Alstom’s projected cash flows.
- Revenue growth assumption in euro terms is a touch higher at 5.36% compared with 5.25%, indicating slightly stronger top line expectations for Alstom.
- Profit Margin assumption has moved modestly higher to 3.91% from 3.86%, signalling a small uplift in expected profitability levels.
- Future P/E multiple is now set at 14.25x versus 15.15x, which points to a slightly more conservative valuation framework for Alstom’s earnings.
Key Takeaways
- Focus on high-quality, margin-accretive orders in Services and Signaling is expected to boost revenue growth and future margins.
- Industrial restructuring and supply chain management improve operational efficiency, enhancing net margins and financial performance.
- Supply chain challenges, low-margin legacy contracts, and immature technology reliance strain Alstom's profitability, cash flows, and future revenue growth prospects.
Catalysts
About Alstom- Provides solutions for rail transport industry in Europe, the Americas, Asia and Pacific, the Middle East, Central Asia, and Africa.
- Alstom's strategy of focusing on high-quality, margin-accretive orders, especially in Services and Signaling, is expected to improve revenue growth and increase future gross margins.
- The company is conducting industrial restructuring to optimize its manufacturing setup, which aims to enhance operational efficiency and potentially improve net margins and earnings.
- Significant future opportunities lie in Alstom's strong order pipeline, especially in Europe, the Middle East, and Asia Pacific, with €200 billion expected in orders over the next three years, which could enhance revenue.
- Alstom's ongoing focus on project execution and mitigating supply chain challenges should lead to more efficient delivery volumes, which may improve both earnings and net margins as production stabilizes.
- Continuous improvement in gross margins in rolling stock and enhanced contract management could lead to better financial performance and higher profitability, enhancing adjusted EBIT and overall earnings.
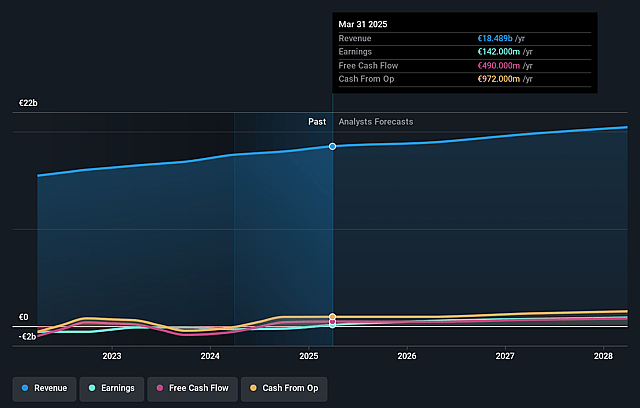
Alstom Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming Alstom's revenue will grow by 5.4% annually over the next 3 years.
- Analysts assume that profit margins will increase from 1.5% today to 3.9% in 3 years time.
- Analysts expect earnings to reach €877.3 million (and earnings per share of €1.88) by about September 2029, up from €279.0 million today.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 14.3x on those 2029 earnings, down from 25.3x today. This future PE is lower than the current PE for the GB Machinery industry at 22.8x.
- Analysts expect the number of shares outstanding to remain consistent over the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 8.66%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Supply chain challenges are causing significant delays in rolling stock production, impacting Alstom's ability to meet contractual deadlines and potentially leading to penalties, affecting future revenue and margins.
- A large portion of the current backlog consists of legacy contracts, which continue to weigh on Alstom’s profitability due to lower margins, impacting net earnings growth.
- The increased inventory levels due to production delays signify potential working capital challenges, which can strain cash flows and impact free cash flow targets.
- The reliance on new technologies with less mature supply chains, such as batteries and fuel cells, poses risks to seamless execution and could affect overall project costs, impacting gross margins.
- Weaker-than-expected market conditions in the Americas and green mobility sectors introduce revenue risks if similar trends persist, potentially affecting future revenue growth.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of €21.1 for Alstom based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of €28.0, and the most bearish reporting a price target of just €10.0.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be €22.4 billion, earnings will come to €877.3 million, and it would be trading on a PE ratio of 14.3x, assuming you use a discount rate of 8.7%.
- Given the current share price of €15.28, the analyst price target of €21.1 is 27.6% higher.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Alstom?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Deteriorating Demand And Rising Costs Will Disrupt Rail Markets
View narrative
Digital Rail And Decarbonization Will Catalyze Urban Growth
View narrative