
Last Update 03 Sep 26
Fair value Increased 13%CGY: Defence Execution And Margin Upgrade Will Support Profitable Repricing
Calian Group’s updated analyst price target has moved from CA$94.07 to CA$106.25, with analysts pointing to recent target increases from CA$90 to CA$105 and from CA$93 to CA$107, supported by updated assumptions on discount rate, revenue growth, profit margin and future P/E.
Analyst Commentary
Recent research on Calian Group points to a cluster of higher price targets, which gives you a window into how bullish analysts are thinking about valuation, execution and growth assumptions today. Even with these higher targets, it remains important to understand what is driving the optimism and where there may still be risks.
Bullish Takeaways
- Bullish analysts have lifted price targets into a range of about CA$105 to CA$107, which signals confidence in Calian Group’s ability to support a higher implied valuation based on their updated models.
- The repeated upward revisions over time, including a move from CA$90 to CA$93 and then above CA$100, indicate that analysts see Calian Group tracking closer to the higher end of their earlier expectations on revenue, margin or P/E assumptions.
- Outperform style ratings paired with higher targets indicate that bullish analysts see Calian Group as relatively attractive against their coverage universe given current execution and growth assumptions.
- The tightening cluster of targets near the current consensus suggests less dispersion in bullish analyst views. This can make it easier for investors to frame upside scenarios within a narrower valuation band.
Bearish Takeaways
- Despite higher targets, ratings remain tied to model assumptions for revenue growth, profit margin and future P/E. Any shortfall in these areas could limit how much of that upside Calian Group delivers in practice.
- The concentration of views around a similar target range can also imply limited room for further target upgrades unless analysts gain new evidence that supports higher growth or margin expectations.
- Outperform style recommendations do not remove execution risk. Calian Group still needs to meet or exceed the assumptions embedded in these models for the higher valuation to be sustained.
- All of the referenced research items lean bullish, so investors may want to balance this with their own assessment of downside scenarios such as softer demand, contract timing or cost pressures that could affect earnings and valuation metrics.
What’s in the News for Calian Group
- Calian Group announced that its UK subsidiary, Calian UK, secured a 15 year agreement with Raytheon UK as part of the Omnia Training consortium to support the British Army's Collective Training Service programme, with approximately CA$296 million (£159 million) in contracted base revenue over the term. Source: Company client announcement.
- The ACTS agreement is expected to begin in October 2026 after the current Project NUMIDIAN contract ends and extends one of Calian Group's largest defence training programs focused on collective training services for the British Army. Source: Company client announcement.
- Calian Group reported that from April 1, 2026 to June 30, 2026, the company repurchased 0 shares for CA$0 million under its buyback program and confirmed completion of the repurchase of 0 shares for CA$0 million under the buyback announced on August 28, 2025. Source: Company buyback tranche update.
- Calian Group announced the formation of the Canadian Arctic Maritime Security Consortium, bringing together six Atlantic organizations to create end to end maritime capability in support of Canada's Arctic and defence priorities, including workforce development and next generation defence capabilities. Source: Company strategic alliance announcement.
- The consortium plans a Canadian Centre of Excellence for Maritime and Arctic Training that will combine advanced simulation, operational training, applied research and digital technologies for the Canadian Armed Forces, Canadian Coast Guard and marine industries. Source: Company strategic alliance announcement.
Valuation Changes for Calian Group
- Fair Value has moved from CA$94.07 to CA$106.25, which points to a higher assessed valuation level for Calian Group under the updated assumptions.
- Discount Rate has shifted from 6.35% to 6.44%. This is a small change that can still influence the present value of future cash flows in the models.
- Revenue Growth has moved from 7.72% to 3.68%, which reflects a lower projected top line growth rate in the updated scenario for Calian Group.
- Net Profit Margin has changed from 3.41% to 4.49%, indicating a higher expected level of profitability on each CA$ of revenue in the new assumptions.
- Future P/E has moved slightly from 35.10x to 35.32x, which keeps the valuation multiple broadly in line with prior expectations while still supporting the higher CA$ fair value outcome.
Key Takeaways
- Strong growth in defense, space, and cybersecurity positions Calian to capitalize on expanding government budgets and heightened digital infrastructure needs.
- Targeted acquisitions and recurring healthcare contracts support margin expansion, diversification, and increased shareholder value through enhanced earnings and buybacks.
- Reliance on defense contracts, acquisition risks, segment underperformance, rising competition, and regulatory pressures threaten revenue stability, margins, and long-term profitability.
Catalysts
About Calian Group- Provides business products and solutions in Canada and internationally.
- Substantial recent growth in the defense business (now 50% of revenues and up 19% YoY) alongside a $1.5 billion backlog and a >$1 billion deal pipeline in Europe positions Calian to benefit from rising global defense spending-especially as public sector budgets in Canada and Europe expand in response to geopolitical instability-supporting strong future revenue and earnings growth.
- Intensifying investments in space and cybersecurity solutions-reinforced by increasing digitalization of critical infrastructure and heightened cyber threats-provide Calian with opportunities for premium, differentiated offerings, which should improve margin mix and drive robust EBITDA growth as these segments expand.
- Ongoing healthcare contract expansions (e.g., AMS acquisition and expanded HCPR contract), as well as the sustained need for healthcare and telehealth solutions driven by aging populations and government recruitment targets, underpin stable and recurring high-margin revenue growth for Calian's health business.
- Strategic M&A focus on high-margin, synergistic targets in defense, healthcare, and advanced tech bolsters diversification, accelerates revenue growth, and broadens Calian's cross-solution capabilities, supporting improved net margins and further enhancing the long-term earnings profile.
- Accelerated buyback activity (5% of shares YTD, targeting 6% for FY25), compounded by strong free cash flow generation and a robust balance sheet, will likely boost EPS and shareholder value as recurring revenue and improved segment performance materialize.
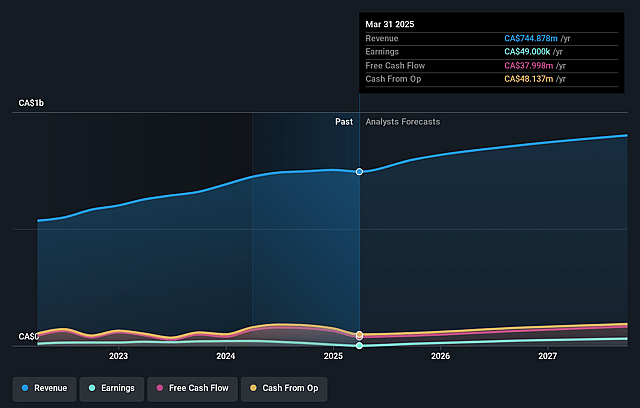
Calian Group Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming Calian Group's revenue will grow by 3.7% annually over the next 3 years.
- Analysts assume that profit margins will increase from 4.4% today to 4.5% in 3 years time.
- Analysts expect earnings to reach CA$43.5 million (and earnings per share of CA$3.73) by about September 2029, up from CA$38.4 million today.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 35.4x on those 2029 earnings, up from 23.1x today. This future PE is greater than the current PE for the CA Commercial Services industry at 25.1x.
- Analysts expect the number of shares outstanding to grow by 1.43% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 6.44%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Persistent underperformance in the ITCS segment-including ongoing 10% revenue decline, management turnover, and delayed recovery-could signal structural challenges or market share loss, potentially eroding overall revenue and compressing margins if not reversed.
- Heavy reliance on government defense budgets (notably in Canada and Europe, where defense now contributes 50% of revenues) creates elevated exposure to political risk, procurement delays, or abrupt budget shifts, which could lead to revenue volatility and unpredictable contract timing.
- Aggressive expansion via acquisitions, while fueling growth, heightens integration risk and raises goodwill and debt levels; future acquisition missteps or rising valuation multiples for targets could trigger impairment charges and impact net earnings.
- Increased global competition in defense, IT, and healthcare services from both multinational primes and niche specialists may drive down average contract margins, dilute differentiation, and force Calian to spend more on sales, marketing, or hiring, thereby pressuring EBITDA and operating profits.
- Rising compliance costs from security, privacy, and ESG regulations, alongside talent shortages and wage inflation in specialized fields like cyber and engineering, risk inflating operating expenses and could constrain net margins and free cash flow over the long term.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of CA$106.25 for Calian Group based on their expectations of its future earnings growth, profit margins and other risk factors.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be CA$969.8 million, earnings will come to CA$43.5 million, and it would be trading on a PE ratio of 35.4x, assuming you use a discount rate of 6.4%.
- Given the current share price of CA$77.1, the analyst price target of CA$106.25 is 27.4% higher.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Calian Group?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Rising Defense And Space Demand Will Support This Undervalued Mission Critical Solutions Provider
View narrative