
Last Update 17 Sep 26
Fair value Increased 4.59%OVV: Acreage Expansion And Buybacks Will Support Bullish Re Rating
Analysts have lifted their price target for Ovintiv to $76.21 from $72.86, citing updated assumptions that include a slightly higher discount rate, a reduced revenue growth outlook, a modestly lower profit margin, and a higher future P/E multiple.
What's in the News for Ovintiv
- Ovintiv outlined progress on its 2026 ground game acquisition program, entering into over 60 transactions year to date that are expected to add about 41,000 net acres across its Montney and Permian assets for a total cost of roughly US$460 million. Source, Company key developments.
- The acquisition program is set to add 240 net 10,000 foot equivalent well locations to Ovintiv's drilling inventory, with 190 base locations and 50 upside locations, at an indicated valuation of about US$11,000 per net acre and roughly US$1.3 million to US$1.7 million per well location. Source, Company key developments.
- Within the Permian basin, Ovintiv is acquiring around 21,000 net acres and 120 total well locations in the Midland basin for about US$230 million. In the Montney play, it is acquiring roughly 20,000 net acres and 120 total well locations in the Alberta oil window, also for about US$230 million. Source, Company key developments.
- For the second quarter ended June 30, 2026, Ovintiv reported total production of 614.6 MBOE/d, with oil production of 123.0 Mbbls/d, Oil and Plant Condensate production of 205.8 Mbbls/d, total liquids production of 288.2 Mbbls/d, and natural gas production of 1,959 MMcf/d. Source, Company key developments.
- Ovintiv issued production guidance for the third quarter and updated its 2026 full year outlook, with expected total production of 615 MBOE/d to 640 MBOE/d for the quarter and 630 MBOE/d to 645 MBOE/d for the year, alongside detailed ranges for Oil and Condensate, NGLs, and natural gas volumes. Source, Company key developments.
- Between April 1, 2026 and June 30, 2026, Ovintiv repurchased 6,105,772 shares for about US$344.85 million, completing a total of 7,593,028 shares repurchased for about US$428.87 million under the buyback program announced on September 29, 2025. Source, Company key developments.
Valuation Changes for Ovintiv
- Fair Value has risen slightly, moving from $72.86 to $76.21 per share.
- Discount Rate has edged higher from 7.11% to 7.24%.
- Revenue Growth assumption has shifted from 1.83% growth to a 1.47% decline.
- Net Profit Margin expectation has eased from 21.13% to 20.24%.
- Future P/E has been reset higher from 14.20x to 17.18x.
Key Takeaways
- Diversified North American gas exposure and new marketing agreements provide revenue stability, pricing power, and support for sustainable long-term margin growth.
- Operational efficiency gains and disciplined capital allocation enhance cost control, production scalability, and drive continued improvement in net margins and shareholder returns.
- Over-dependence on North American shale and evolving industry pressures could threaten Ovintiv's long-term growth, margins, and competitiveness amidst shifting energy trends and increasing regulation.
Catalysts
About Ovintiv- Explores, develops, produces, and markets natural gas, oil, and natural gas liquids in North America.
- Anticipated growth in global energy demand-driven by economic expansion in emerging markets and a slower pace of energy transition-provides a structurally strong backdrop for hydrocarbon pricing and Ovintiv's revenue and free cash flow over the long term.
- Ovintiv's diversified North American natural gas exposure, reinforced by new marketing agreements (e.g., JKM and Chicago-linked contracts) and positioning for LNG exports, supports volume stability and higher realized prices, positively impacting revenue consistency and margin resilience.
- Significant operational efficiency improvements (driven by AI-enabled optimization, rapid asset integration, and 'cube' development) are reducing per-barrel costs and capital intensity, supporting ongoing net margin expansion regardless of the broader commodity price cycle.
- Deep premium drilling inventory in high-return shale plays (Permian, Montney, Anadarko) underpins sustainable production growth, scale-driven cost advantages, and long-term top-line growth potential.
- Disciplined capital allocation (including structural cost reductions, debt paydown, and aggressive share buybacks) is set to drive durable increases in earnings per share and further upside for equity valuation as capital markets recognize improved net margins and cash flow per share growth.
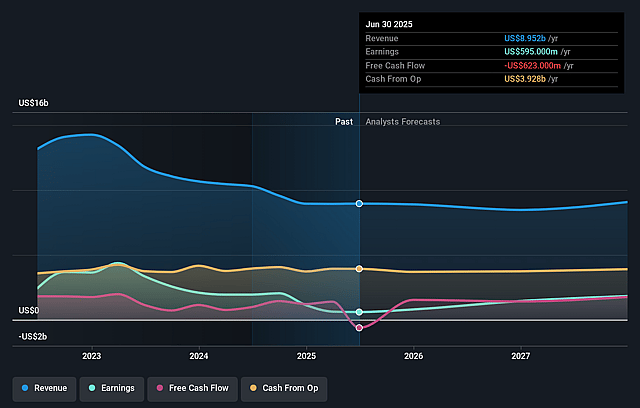
Ovintiv Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming Ovintiv's revenue will decrease by 1.5% annually over the next 3 years.
- Analysts assume that profit margins will increase from 9.7% today to 20.2% in 3 years time.
- Analysts expect earnings to reach $1.8 billion (and earnings per share of $7.34) by about September 2029, up from $920.0 million today. However, there is a considerable amount of disagreement amongst the analysts with the most bullish expecting $2.6 billion in earnings, and the most bearish expecting $1.3 billion.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 17.2x on those 2029 earnings, down from 18.8x today. This future PE is greater than the current PE for the US Oil and Gas industry at 13.2x.
- Analysts expect the number of shares outstanding to grow by 7.0% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 7.24%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Ovintiv's heavy reliance on North American shale exposes it to regional price differentials, basin-specific downturns, and potential supply gluts (such as the historic oversupply referenced in the Canadian gas market), which could undermine long-term revenue stability and lead to periods of margin compression.
- Despite current cost efficiencies, persistent inflation in oilfield services, labor, and materials-or a reversal of current service cost deflation-could erode capital efficiency and margins if Ovintiv cannot continue to offset these pressures through operational improvements.
- Accelerating energy transition trends, technological advancements in renewables and battery storage, and increasing regulatory requirements for emissions and ESG compliance may structurally diminish long-term demand for oil and gas, shrinking Ovintiv's addressable market and potentially impacting future earnings and cash flows.
- The company's long-term inventory longevity depends on continued successful reserve replacement and the quality of its undeveloped locations; if core assets mature faster than expected or if upside drilling opportunities do not materialize, production volumes could decline, negatively impacting future revenue and share price growth.
- Growing competition and ongoing consolidation in Montney and U.S. shale could erode Ovintiv's cost advantages over time or limit its ability to acquire new high-return acreage at attractive prices, constraining future top-line growth and reducing opportunities for sustained net margin expansion.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of $76.21 for Ovintiv based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $92.0, and the most bearish reporting a price target of just $55.0.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $9.1 billion, earnings will come to $1.8 billion, and it would be trading on a PE ratio of 17.2x, assuming you use a discount rate of 7.2%.
- Given the current share price of $62.77, the analyst price target of $76.21 is 17.6% higher.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Ovintiv?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Regulatory Risks Will Curb Permian Production While Cautious Hope Emerges
View narrative
North American Shale Will Benefit From Rising Global Energy Demand
View narrative