
Last Update 10 Sep 26
Fair value Increased 2.13%3711: Future Returns Will Rely On Stable Margins And Panel Packaging
Analysts have modestly raised their price target for ASE Technology Holding to NT$707.47 from NT$692.74, reflecting updated views on fair value, profit margin assumptions, and future P/E expectations, while keeping the discount rate unchanged.
What's in the News
- ASE Technology Holding issued consolidated earnings guidance for the third quarter of 2026, providing updated expectations for revenue and operating margin performance. Source: Key Developments
- The company expects consolidated third quarter 2026 revenue, in NT dollar terms, to grow by 21% to 22% quarter over quarter. Source: Key Developments
- ASE Technology Holding guided for a consolidated third quarter 2026 operating margin in a range of 11.5% to 12.5%. Source: Key Developments
Valuation Changes for ASE Technology Holding
- The fair value has risen slightly, with the NT$ price target moving from NT$692.74 to NT$707.47.
- The discount rate is unchanged at 11.19%, indicating no adjustment to the required return assumption.
- The revenue growth expectation is marginally lower, moving from 24.76% to 24.59%.
- The net profit margin assumption is slightly higher, increasing from 14.16% to 14.24%.
- The future P/E multiple has risen slightly, moving from 21.91x to 22.34x.
Key Takeaways
- Diversified growth in advanced packaging, automation, and new technologies is driving higher-margin potential and positioning ASE as a key industry player for next-generation demands.
- Margin pressures from costs and foreign exchange are expected to ease as automation ramps and value-added services enable more stable, resilient, and diversified earnings.
- Persistent currency volatility, capacity constraints, rising leverage, market cyclicality, and geopolitical risks collectively threaten ASE's margins, scaling ability, earnings stability, and global competitiveness.
Catalysts
About ASE Technology Holding- Provides semiconductor manufacturing services in assembly and testing in the United States, Taiwan, Europe, Asia, and internationally.
- ASE is experiencing strong, multi-year demand driven by the expansion of global data centers, proliferation of AI applications, and increasing semiconductor content per device across end-markets. This should support sustained revenue growth into 2026 and beyond as advanced packaging and testing needs accelerate.
- Investments in leading-edge technologies (3D IC, chiplet, system-in-package, silicon photonics) and aggressive capacity expansion-especially in advanced packaging/test and fully automated lines-position ASE as a key player to meet next-generation requirements, enabling higher-margin mix and long-term operating margin expansion.
- The increasing pace of digital transformation in automotive, industrial, and networking segments is boosting high-margin demand for ASE's services outside traditional consumer electronics, supporting more stable and resilient earnings and diversifying revenue streams.
- Margins are temporarily pressured by foreign exchange headwinds and early ramp-up costs, but management anticipates a return to structural margin levels by 2026 as utilization improves, cost efficiencies from automation ramp, and pricing recalibrates to reflect value-added capabilities, benefiting future net margins and earnings.
- Tight capacity environment and high CapEx investments today are largely customer-driven, with long-term orders and ecosystem partnerships in place. As these capacity additions come online and resource optimization initiatives take effect, ASE can better leverage scale, capture incremental volume, and realize improved returns on capital, positively impacting future operating and net margins.
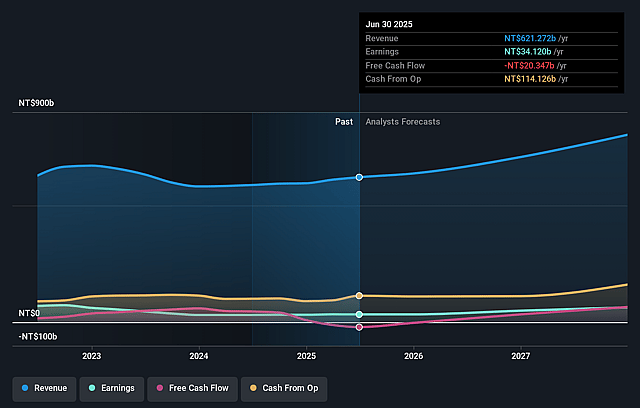
ASE Technology Holding Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming ASE Technology Holding's revenue will grow by 24.6% annually over the next 3 years.
- Analysts assume that profit margins will increase from 8.5% today to 14.2% in 3 years time.
- Analysts expect earnings to reach NT$195.9 billion (and earnings per share of NT$36.04) by about September 2029, up from NT$60.8 billion today. However, there is a considerable amount of disagreement amongst the analysts with the most bullish expecting NT$220.9 billion in earnings, and the most bearish expecting NT$144.7 billion.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 22.3x on those 2029 earnings, down from 47.0x today. This future PE is lower than the current PE for the US Semiconductor industry at 31.0x.
- Analysts expect the number of shares outstanding to grow by 0.78% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 11.19%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Persistent foreign exchange volatility, particularly NT dollar appreciation against the US dollar, is having a significant and direct negative impact on ASE's gross and operating margins; this currency risk remains a structural threat that could continue to erode profitability and reported earnings if left unmitigated.
- The company is facing substantial resource constraints-including execution risk, human talent shortages, land, facility, and machine delivery issues-that are limiting its ability to rapidly scale capacity to meet surging demand, potentially resulting in missed revenue opportunities and higher operational pressure.
- Ongoing, heavy capital expenditures funded through rising debt are increasing financial leverage and net debt-to-equity ratios; if anticipated returns or market growth do not materialize as planned, this creates long-term pressure on net margins and could limit financial flexibility.
- There are signs of market disparity and potential cyclicality, with non-AI segments (such as PC, smartphone, and general EMS) described as slow or inconsistent; over-reliance on the AI and advanced packaging/testing wave exposes ASE to earnings volatility if there is a pause or slowdown in that domain.
- Geopolitical risks and regulatory controls-including evolving tariffs, BIS restrictions, and worldwide deglobalization trends-may require costly overseas investments, resource diversion, or loss of market access, all of which threaten revenue growth and global competitiveness in the longer term.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of NT$707.47 for ASE Technology Holding based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of NT$840.0, and the most bearish reporting a price target of just NT$545.0.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be NT$1375.3 billion, earnings will come to NT$195.9 billion, and it would be trading on a PE ratio of 22.3x, assuming you use a discount rate of 11.2%.
- Given the current share price of NT$650.0, the analyst price target of NT$707.47 is 8.1% higher. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on ASE Technology Holding?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

AI Data Center Packaging Dependence Will Likely Pressure Margins And Limit Long Term Upside
View narrative
AI Data Center Packaging And Photonics Will Drive Powerful Long-Term Upside
View narrative