
Last Update 18 Aug 26
Fair value Decreased 7.26%KEMIRA: AI Water Solutions Will Offset Margin Risks And Support Steady Outlook
The analyst price target for Kemira Oyj has been reduced from €20.43 to €18.95 as analysts factor in concerns that margin goals could be hard to reach if raw material prices stay volatile and demand remains weak.
What’s in the News for Kemira Oyj
- Kemira Oyj reiterated earnings guidance for 2026 and expects revenue to be between €2,600 million and €3,000 million. Source: company guidance.
- The company updated its 2026 outlook and now expects revenue between €2,600 million and €3,000 million while downgrading profitability expectations due to higher raw material and logistics costs linked to the prolonged war in Iran and weaker demand in key customer industries. Source: company guidance.
- Kemira Oyj reported that from April 1, 2026 to June 16, 2026 it repurchased 3,070,512 shares for €57.92 million. This completed a buyback of 5,000,000 shares for €94 million that represents 3.37% of shares under a program announced on February 12, 2026. Source: company buyback update.
- Kemira and CuspAI announced progress in using generative AI to design new metal organic framework materials aimed at removing PFAS or forever chemicals from drinking and process water at trace concentrations. The project screened about 300 trillion possible structures, produced more than 5,000 candidate materials and narrowed this to around 20 priority candidates in six months. Source: product-related announcement.
Valuation Changes for Kemira Oyj
- Fair value reduced from €20.43 to €18.95, which is a modest cut of around 7%.
- Discount rate edged up slightly from 6.61% to 6.72%.
- Revenue growth adjusted marginally lower from 3.43% to 3.39%.
- Net profit margin revised slightly higher from 7.72% to 7.81%.
- Future P/E lowered from 13.74x to 12.16x, indicating a meaningfully lower valuation multiple applied to Kemira Oyj.
Key Takeaways
- Expanding water solutions and bio-based material partnerships position the company to benefit from global sustainability trends and tighter regulations.
- Profitability initiatives, digitalization, and geographic diversification support margin improvement and stable long-term growth prospects.
- Weak end-markets, profitability challenges, and currency volatility threaten Kemira's earnings and growth, while mature industries, competition, and cash flow constraints risk long-term market relevance.
Catalysts
About Kemira Oyj- Operates as a chemicals company in Finland, rest of Europe, the Middle East, Africa, the Americas, and the Asia Pacific.
- Kemira's core Water Solutions business remains resilient and benefits from increasing global demand for clean water and tightening water treatment regulations; ongoing investments and strategic capacity expansions (including innovation partnerships for AI-based material development) are poised to support top-line revenue growth and margin resilience as these regulatory trends strengthen globally.
- The company is actively participating in the shift toward renewable and recycled packaging materials, demonstrated by R&D partnerships (e.g., with Bluepha and Metsä Group) to commercialize fully bio-based materials; this positions Kemira to gain share as ESG and sustainability priorities accelerate, offering future revenue and margin tailwinds as customers seek greener alternatives.
- Execution of a broad profitability improvement program in the Packaging & Hygiene Solutions segment-especially in APAC, where margins are weakest-is expected to deliver significant EBITDA and net margin improvement over the next year through cost base reductions and targeted volume recovery.
- Maintenance of a strong balance sheet and launch of a sizable share buyback program highlight substantial capital allocation flexibility, enabling continued investment in organic and inorganic growth-supporting higher prospective EPS and return on equity as M&A and capacity expansions are executed.
- Strengthening Kemira's presence in high-growth regions (such as North America and select emerging markets), along with ongoing digitalization and value-added specialty chemical innovation, provides a structural platform for stable long-term revenue growth and improvement in earnings quality.
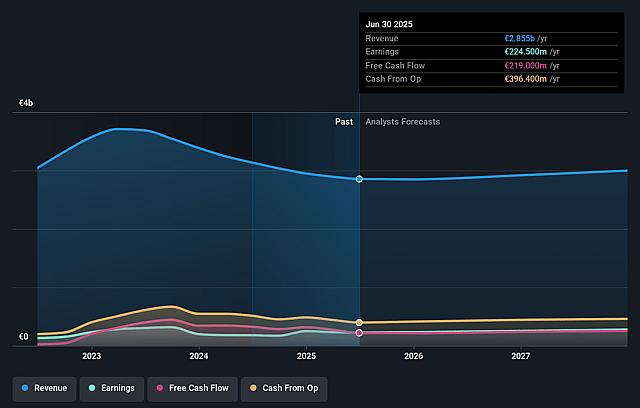
Kemira Oyj Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming Kemira Oyj's revenue will grow by 3.4% annually over the next 3 years.
- Analysts assume that profit margins will increase from 5.3% today to 7.8% in 3 years time.
- Analysts expect earnings to reach €234.9 million (and earnings per share of €1.59) by about August 2029, up from €145.0 million today. However, there is some disagreement amongst the analysts with the more bullish ones expecting earnings as high as €291.8 million.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 12.2x on those 2029 earnings, down from 17.3x today. This future PE is lower than the current PE for the GB Chemicals industry at 17.3x.
- Analysts expect the number of shares outstanding to decline by 5.02% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 6.72%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Kemira's revenue and organic growth are under sustained pressure from structurally weak end-markets such as Packaging & Hygiene Solutions (PHS) and softness in the pulp industry-suggesting that mature industries and digitalization trends could continue to constrain long-term revenue and volume growth.
- Persistent profitability challenges and negative organic growth in PHS, especially in APAC, highlight Kemira's high fixed cost leverage; if cost-saving measures and volume gains in the segment do not materialize as planned, it could compress net margins and ultimately depress overall earnings.
- Exchange rate volatility, particularly the weakening U.S. dollar, significantly impacts Kemira's reported revenue and EBITDA, exposing the company to unpredictable headwinds that can erode margins and earnings, especially given its international exposure.
- Kemira's ability to optimize working capital and generate adequate operating cash flow is already strained during periods of declining revenue-continued inventory and receivables imbalances amid softened growth could impede future investments, return of capital, and inorganic growth opportunities.
- Heavy reliance on mature geographic markets and core industries (pulp & paper, water treatment) that face structural or secular stagnation, alongside emerging competition from alternative green/biotech water treatment solutions, could gradually erode Kemira's addressable market and revenue streams, directly threatening its long-term growth outlook.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of €18.95 for Kemira Oyj based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of €22.0, and the most bearish reporting a price target of just €16.2.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be €3.0 billion, earnings will come to €234.9 million, and it would be trading on a PE ratio of 12.2x, assuming you use a discount rate of 6.7%.
- Given the current share price of €17.33, the analyst price target of €18.95 is 8.5% higher. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Kemira Oyj?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Water Treatment Expansion And Cost Efficiencies Will Support Stronger Long Term Earnings Resilience
View narrative
Micropollutant Projects And Cost Pressures Will Shape A Balanced Outlook
View narrative