Advertisement
- Hong Kong
- /
- Industrials
- /
- SEHK:19
How Investors Are Reacting To Swire Pacific (SEHK:19) Boosting Its Stake in Cathay Pacific
SI

Reviewed by Sasha Jovanovic
- State-owned Qatar Airways has in the past sold its entire US$897 million stake in Cathay Pacific Airways, with Cathay Pacific repurchasing the 9.7 percent holding, marking Qatar Airways' complete exit after eight years.
- This buyback has increased Swire Pacific's ownership in Cathay Pacific to 47.69 percent from 43.12 percent, strengthening its influence and alignment with the airline's future direction and growth initiatives.
- We'll examine how Swire Pacific’s increased stake in Cathay Pacific may impact its investment narrative and long-term strategic outlook.
These 13 companies survived and thrived after COVID and have the right ingredients to survive Trump's tariffs. Discover why before your portfolio feels the trade war pinch.
Swire Pacific Investment Narrative Recap
Being a Swire Pacific shareholder hinges on confidence in the resilience and growth of its core businesses, particularly real estate in Mainland China and the ongoing recovery in aviation through Cathay Pacific. The recent increase in Swire Pacific's stake in Cathay Pacific, following Qatar Airways' exit, further aligns its fortunes with the airline; however, this shift does not materially alter the key short-term catalyst, Asia-Pacific air travel recovery, or the biggest risk: ongoing earnings volatility tied to aviation sector swings.
Among recent announcements, Swire Pacific's ongoing share buyback program stands out, having repurchased more than 11 percent of its shares since late 2023. This is particularly relevant as it underscores management's continued commitment to capital returns, even as aviation sector uncertainty and property market pressures remain central themes for the business.
By contrast, investors should also be alert to how changes in aviation market conditions could affect Swire Pacific's consolidated earnings and...
Read the full narrative on Swire Pacific (it's free!)
Swire Pacific's outlook anticipates revenue of HK$107.5 billion and earnings of HK$13.8 billion by 2028. This scenario is based on a 6.8% annual revenue growth rate and a HK$12.6 billion increase in earnings from current levels of HK$1.2 billion.
Uncover how Swire Pacific's forecasts yield a HK$79.50 fair value, a 19% upside to its current price.
Exploring Other Perspectives
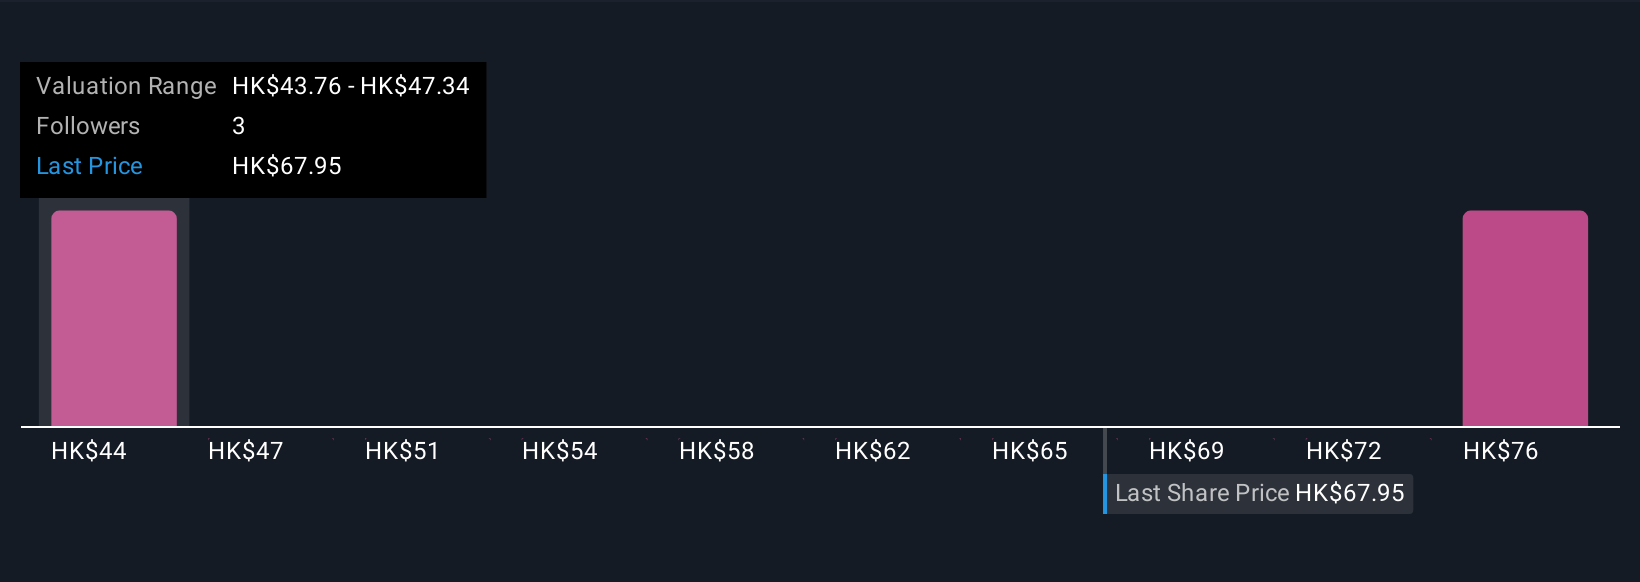
Simply Wall St Community members currently offer two fair value estimates for Swire Pacific, from HK$37.06 to HK$79.50, signaling broad differences in outlook. With aviation sector volatility still a defining risk, exploring a range of viewpoints can help you understand what's most likely to influence results in the year ahead.
Explore 2 other fair value estimates on Swire Pacific - why the stock might be worth 44% less than the current price!
Build Your Own Swire Pacific Narrative
Disagree with existing narratives? Create your own in under 3 minutes - extraordinary investment returns rarely come from following the herd.
- A great starting point for your Swire Pacific research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- Our free Swire Pacific research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate Swire Pacific's overall financial health at a glance.
Contemplating Other Strategies?
Right now could be the best entry point. These picks are fresh from our daily scans. Don't delay:
- The end of cancer? These 29 emerging AI stocks are developing tech that will allow early identification of life changing diseases like cancer and Alzheimer's.
- Rare earth metals are the new gold rush. Find out which 35 stocks are leading the charge.
- Trump's oil boom is here - pipelines are primed to profit. Discover the 22 US stocks riding the wave.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
MI

The Foxhole
A landmark settlement is meant to punish Meta (META). If the 1998 tobacco deal is any guide, it might protect it.
108
ZO
zoe_vi5fn
Any moat with an opt-out clause for your competitors is just a fence around your own garden.
CO
connor_iwn1g
Worth looking at what previous legal action actually did to Meta rather than reaching for tobacco. The FTC's record five billion dollar privacy fine in 2019 was met with the stock rising, because it came in below fears and removed an open question. GDPR was designed to constrain large platforms and increased their share of the European ad market, because compliance cost fell hardest on small intermediaries. The FTC's antitrust case, the one that could genuinely have broken the company up, was decided in Meta's favour last November. The only thing that ever meaningfully hurt the business was Apple changing a tracking default, and Meta out-spent that too, while the ad-tech firms that could not afford to rebuild disappeared. The pattern is not that Meta survives regulation. It is that regulation keeps costing its smaller competitors more.
 Andrew Legget
Market Insights
Great earnings season, but are the earnings real?
At first glance, this was the strongest earnings season in years. But when you look at where the growth actually came from, the story splits into two very different pictures.
10
About SEHK:19
Swire Pacific
Engages in the property, aviation, beverages, marine, and trading and industrial businesses in Hong Kong, Mainland China, Taiwan, rest of Asia, the United States, and internationally.
Solid track record with mediocre balance sheet.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.5% undervalued
26 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
TR


tripledub on Meta Platforms ·
The $135 Billion Bet That Should Make Every Shareholder Nervous
Fair Value:US$5861.4% undervalued
59 followersusers have followed this narrative
3 commentsusers have commented on this narrative
34 likesusers have liked this narrative
TA


Talos on Voyager Technologies ·
The "Landlord of Orbit" – A Deep Value Play Ahead of the Starlab Era
Fair Value:US$385.291.1% undervalued
62 followersusers have followed this narrative
0 commentsusers have commented on this narrative
6 likesusers have liked this narrative
IV

Ivoed on Uber Technologies ·
Uber’s Valuation Depends On Who Captures The Economics Of Driverless Rides
Fair Value:US$11632.1% undervalued
12 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
RO


RockeTeller on Santacruz Silver Mining ·
Santacruz Silver, 5.6M Oz Silver Producer Trading at Low Multiples, 100X Per-Share Upside in $200 Silver
Fair Value:CA$142.990.7% undervalued
96 followersusers have followed this narrative
14 commentsusers have commented on this narrative
0 likesusers have liked this narrative
CO


composite32 on Eaton ·
"Grid-to-Chip: How Eaton Controls the Physical Bottlenecks of AI Data Centers"
Fair Value:US$517.0622.1% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
QU


QuanD on NVIDIA ·
Nvidia Isn’t Cisco. And It’s Still Cheap
Fair Value:US$359.2239.4% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS

oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28022.3% undervalued
365 followersusers have followed this narrative
9 commentsusers have commented on this narrative
16 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9122.3% overvalued
213 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
KI

KiwiInvest on Amazon.com ·
Amazon's high growth, high tech segments propel its profits, while traditional segments plod along
Fair Value:US$475.0943.9% undervalued
240 followersusers have followed this narrative
1 commentusers have commented on this narrative
8 likesusers have liked this narrative
Trending Discussion

DA

david_8pjjo on Axon Enterprise ·
One factor to consider for Axon's growth is whether the Russia - Ukraine war continues. Axon's Dedrone (dead drone) product could be a game changer, however if it is too successful, it could lead to an end of the war, thereby reducing Dedrone sales - an unintended consequence!David Lane
0
|0
