Lotus Bakeries (ENXTBR:LOTB) may not be grabbing headlines with a dramatic event or shock announcement this week, but the stock’s recent movements are enough to get investors thinking. Sometimes, it takes just a gradual shift in momentum or an unremarkable earnings season to prompt a fresh look at a company’s value and growth story, especially for those tracking the food and beverage sector. With the absence of a major trigger, the real story may simply be how investors are reassessing what comes next for this long-standing Belgian giant.
Over the past year, Lotus Bakeries’ share price has seen more downs than ups, dipping around 28%. Recent weeks have seen the stock bounce modestly in the last month, but year-to-date momentum remains negative. This follows a period of significant long-term growth and healthy annual increases in both revenue and net income, reminding market watchers that history often matters when judging risk versus potential.
Given the softer tone in recent performance, are shares now attractively priced for patient buyers, or is the market already baking future growth into the current valuation?
Advertisement
Most Popular Narrative: 11.7% Undervalued
According to the most widely cited narrative, Lotus Bakeries appears undervalued by 11.7%, based on analysts' future growth and profit expectations and a discount rate of 5.97%.
The strategic partnership with Mondelez aims to expand the Biscoff brand in India and co-create new chocolate products in Europe. This has the potential to increase revenue through new product lines and market penetration. The construction of a new greenfield production facility in Thailand, expected to be operational by mid-2026, is planned to support growth in the Asia Pacific region. This could lead to revenue expansion and economies of scale that improve net margins.
Wondering what powers this bullish valuation call? The analysts cite rapid international expansion and sizable jumps in profitability as game changers. What assumptions have they made about sales growth, profit margins, and the company's future earning power? Find out which bold projections are baked into their price target and why some experts think this stock's best days are still ahead.
However, delayed facility completion and rising raw material costs could challenge the upbeat outlook. These factors may put pressure on revenue growth and profit margins going forward.
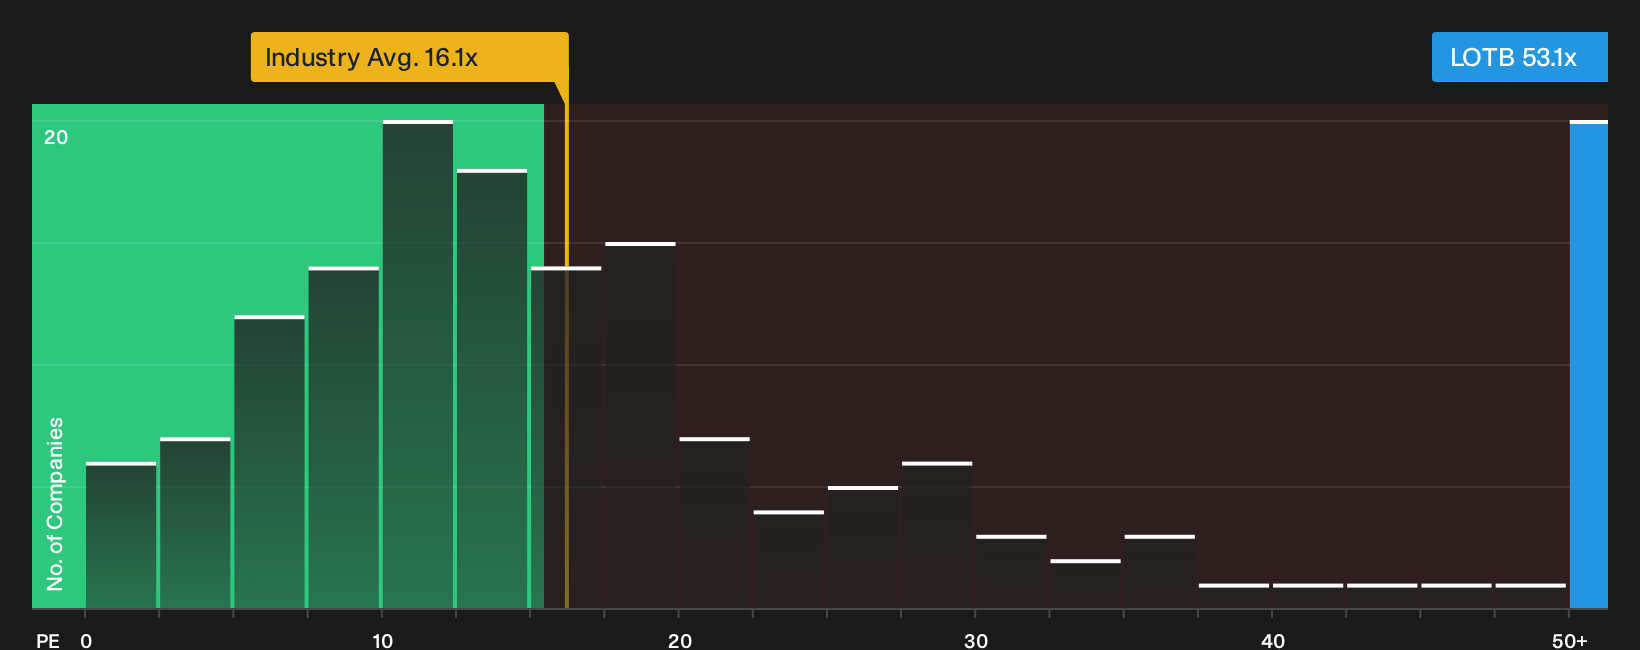
Looking at valuation from another angle, the standard measure for food stocks suggests Lotus Bakeries commands a far higher price tag than the broader industry. Is this a warning sign, or just a premium for quality? Which story do you trust?
Stay updated when valuation signals shift by adding Lotus Bakeries to your watchlist or portfolio. Alternatively, explore our screener to discover other companies that fit your criteria.
Build Your Own Lotus Bakeries Narrative
If you see things differently or want to uncover your own story in the numbers, take a few minutes to explore the details for yourself, then Do it your way.
A good starting point is our analysis highlighting 2 key rewards investors are optimistic about regarding Lotus Bakeries.
Looking for more investment ideas?
Don't let your next big opportunity pass you by. When you use the Simply Wall Street Screener, you gain access to investment themes and hidden gems that most people miss.
Spot high-yield opportunities by searching for rock-solid firms offering generous payouts using dividend stocks with yields > 3%.
Get ahead of financial innovation and see which up-and-coming names are set to benefit from the AI revolution with AI penny stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield) • Undervalued Small Caps with Insider Buying • High growth Tech and AI Companies
Druckenmiller says cheap money's days are numbered. Boring, self-funding companies could be the opportunity.
1311
DE
devon_jd150•
Leverage on its own is close to useless as a screen right now, because so much corporate debt was termed out at 2 to 3% and has not repriced. A business at three times leverage with nothing due until 2031 is in a completely different position from the same ratio rolling next year. Screen on weighted average maturity and the schedule behind it.
LE
LeverageIsLovely•
In my view, Insurance companies are best positioned for this.
Kshitija (or Keisha) Bhandaru is an Equity Analyst at Simply Wall St and has over 6 years of experience in the finance industry and describes herself as a lifelong learner driven by her intellectual curiosity. She previously worked with Market Realist for 5 years as an Equity Analyst.


 Mitchell Lawler