
Last Update 03 Sep 26
Fair value Increased 5.99%JBHT: Tight Capacity And Intermodal Momentum Will Support Shares Into 2027
Analysts have raised their blended fair value estimate for J.B. Hunt Transport Services to about $305 per share from roughly $288. This reflects updated models that factor in stronger than expected Q2 results, ongoing intermodal volume gains, and expectations for a healthier truckload pricing cycle and earnings profile into 2027.
Analyst Commentary
Recent Street research on J.B. Hunt Transport Services points to a wide range of views on how far the stock price already reflects the Q2 strength in intermodal and expectations for a healthier truckload cycle into 2027. Price targets now span roughly US$200 to US$370, which signals differing opinions on both execution risks and how much investors are willing to pay for that earnings path.
Bullish Takeaways
- Bullish analysts highlight Q2 results that came in ahead of forecasts, with several pointing to stronger intermodal margins, 10% volume growth and better core pricing as support for higher earnings power and higher price targets.
- Many see tightening truckload capacity and a healthier pricing cycle as key drivers for profit growth into 2027, and some describe J.B. Hunt as a prime beneficiary of freight shifting to intermodal as rail service and truckload discounts improve.
- Supportive views often cite structural cost reductions, productivity gains and earlier investments in intermodal and dedicated fleets as reasons the company can translate volume gains into a stronger earnings profile.
- Several bullish analysts, including those at JPMorgan, Baird, Wells Fargo, Stephens and BofA, frame J.B. Hunt as well positioned to benefit if freight demand and pricing trends stay constructive over the next few years.
Bearish Takeaways
- Bearish analysts and some with Neutral or Hold ratings argue that much of the expected recovery in truckload pricing and intermodal growth is already reflected in the current valuation, which limits potential upside if earnings only track existing forecasts.
- Morgan Stanley maintains an Underweight stance even with a higher price target, highlighting concerns that the freight cycle is already elevated and could see volatility, which may create a less favourable risk or reward profile from current levels.
- Several Hold and Neutral ratings, including from UBS and Truist, signal caution that while Q2 execution was strong, investors may be paying a full multiple for earnings that still depend on a supportive truckload and intermodal backdrop into 2027.
- Some research points out that alternative transport stocks, such as less than truckload and brokerage peers, are viewed as more attractive ways to gain exposure to a freight recovery, which could cap relative valuation for J.B. Hunt if those peers outperform.
What’s in the News for J.B. Hunt Transport Services
- J.B. Hunt executives highlight that keeping drayage operations in house can be a competitive advantage as the supply of drayage drivers remains tight, according to comments from Darren Field, EVP and President of Intermodal. Source: recent carrier and trucking industry coverage.
- Major carriers, including J.B. Hunt Transport Services, report that shrinking driver supply continues to pressure capacity, especially for drayage services. This is driving a focus on efficiency and tighter control of internal operations. Source: recent drayage and trucking labor news.
- Trucking executives at J.B. Hunt and peers are concentrating on efficiency strategies that aim to maximize existing fleets and limit the need for outside drayage providers in order to retain customers and compete for new business. Source: carrier and freight sector reporting.
- From April 1, 2026 to June 30, 2026, J.B. Hunt Transport Services repurchased 391,758 shares for US$97.77 million, which completed a total of 967,435 shares repurchased for US$209.83 million under the buyback that was announced on October 22, 2025.
- J.B. Hunt Transport Services was added to the Russell 1000 Dynamic Index, which places the stock inside an additional equity benchmark followed by some institutional investors.
Valuation Changes for J.B. Hunt Transport Services
- Fair Value has risen slightly, with the blended estimate moving from about $288.18 per share to roughly $305.45 per share.
- Discount Rate has increased modestly from 8.15% to about 8.26%, which points to a slightly higher required return in the updated model.
- Revenue Growth has been marked higher in the assumptions, shifting from 8.35% to roughly 8.91%.
- Net Profit Margin has edged lower, moving from about 6.88% to roughly 6.71% in the new forecast for J.B. Hunt Transport Services.
- Future P/E has been set higher, changing from about 29.88x to roughly 31.66x, which indicates a richer multiple in the refreshed valuation work.
Key Takeaways
- Improved equipment utilization and cost optimization efforts enhance operational efficiencies, positively affecting net margins and profitability.
- Strategic investments in technology and capacity expansion support long-term revenue growth by accessing large addressable markets.
- Inflationary pressures, competitive rates, and muted demand in key segments challenge margins and earnings amidst an uncertain macroeconomic and policy environment.
Catalysts
About J.B. Hunt Transport Services- Provides surface transportation, delivery, and logistic services in the United States.
- Record first quarter intermodal volumes could indicate an ability to capture more market share, contributing to potential revenue growth.
- Efforts to improve equipment utilization and reduce empty move costs may enhance operational efficiencies, positively impacting net margins.
- Strategic investments in technology and capacity expansion may provide a platform for long-term revenue growth by better serving large addressable markets.
- Successful bid season outcomes, including modest rate increases and filling costly empty lanes, could drive better revenue and profitability metrics.
- The focus on reducing and optimizing costs, combined with a disciplined capital allocation strategy, suggests improvements in earnings as the company scales operations.
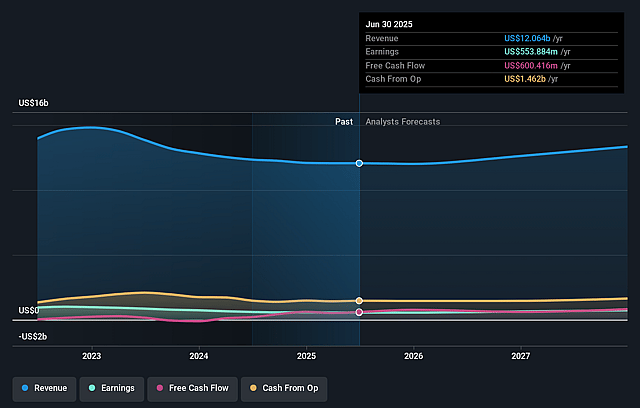
J.B. Hunt Transport Services Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming J.B. Hunt Transport Services's revenue will grow by 8.9% annually over the next 3 years.
- Analysts assume that profit margins will increase from 5.3% today to 6.7% in 3 years time.
- Analysts expect earnings to reach $1.1 billion (and earnings per share of $12.3) by about September 2029, up from $674.5 million today. However, there is some disagreement amongst the analysts with the more bullish ones expecting earnings as high as $1.3 billion.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 31.7x on those 2029 earnings, down from 36.2x today. This future PE is lower than the current PE for the US Transportation industry at 35.7x.
- Analysts expect the number of shares outstanding to decline by 1.37% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 8.26%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- The company faces a challenging operating environment with inflationary cost pressures more than offsetting productivity improvements, affecting margins and earnings.
- Lower yields and increased insurance premiums have been weighing on operating income, indicating potential pressure on net margins and earnings.
- Seasonally lower volume and rate pressure coupled with competitive truckload rates, especially in the Eastern network, may limit the ability to achieve desired price increases and hurt revenue and margins.
- Demand for Final Mile services such as furniture and appliances remains muted, potentially impacting revenue and margin growth in this segment.
- The uncertain macro environment and changing trade policies, including tariffs, pose risks to supply and demand dynamics, which could impact revenue and profitability.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of $305.45 for J.B. Hunt Transport Services based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $370.0, and the most bearish reporting a price target of just $182.0.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $16.4 billion, earnings will come to $1.1 billion, and it would be trading on a PE ratio of 31.7x, assuming you use a discount rate of 8.3%.
- Given the current share price of $260.22, the analyst price target of $305.45 is 14.8% higher.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on J.B. Hunt Transport Services?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Prefunded Intermodal Capacity And Cost Efficiencies Will Transform Long Term Earnings Power
View narrative
Intermodal Investments And Rail Shifts Will Pressure Margins And Limit Long Term Earnings
View narrative